Sellers ask me whether a homeowners association can block a closing. It can’t. What an HOA can do is sit on paperwork long enough that your escrow agent starts making daily phone calls, and I’ve seen that delay sink more Oregon sales than any inspection report I’ve read. Dues, a transfer fee, and a resale packet nobody budgeted for: all three hit the settlement statement at the same moment. Owners who understand the order of those line items keep more of the sale price. Let’s take them one at a time, starting with the debt that eats the biggest share of your check.
Does the Seller Pay Off Liens and Mortgages at Closing?
“Can’t the buyer just take over my loan?”
Almost never. Your mortgage gets paid off out of the proceeds on closing day, and the escrow agent handles it without you lifting a finger. Escrow orders a payoff demand from your lender, confirms the good-through date, and wires the money before recording the deed, a step I’ve seen go smoothly even in messy closings. Anything left over is yours.
Liens work the same way, but they’re less predictable. A title search can surface an old judgment, a contractor’s lien from a deck project, a state tax warrant, or unpaid association assessments nobody told you about. Each one has to clear before the title company will insure the buyer’s ownership. Catching that isn’t your real estate agent’s job. The title company finds them, and then the clock starts. If one turns up on yours, here’s whether you can sell a house with a lien in Portland, OR.
With Oregon’s median sale price sitting at $506,889 in August 2026, according to Redfin’s statewide tracking, most sellers have enough equity to clear their debts and still walk away whole. Most. Not all.
Who Pays to Record the Sale with Local Government in Oregon?
Sit down with me at your kitchen table, and I’ll tell you the same thing I tell everyone: recording fees are the cheapest line on the whole statement, and they’re still worth asking about.
Your county clerk or recording division charges a flat fee for the first page of a document plus a smaller amount per additional page. Statewide, a deed usually runs around a hundred dollars to record. Custom in most Oregon transactions puts the deed recording on the buyer, since the buyer’s the one getting the title, so that cost rarely becomes a negotiating point. Releases of your old mortgage and any lien satisfactions land on you, the seller.
Washington County is the exception to everything.
Property in Beaverton, Hillsboro, Tigard, or Tualatin carries a real estate transfer tax of one dollar per thousand dollars of the selling price under the county’s transfer tax ordinance. On a half-million-dollar sale, that’s five hundred bucks. Oregon law otherwise bars cities and counties from taxing property transfers; ORS 306.815 blocks the practice, and Washington County’s ordinance survives only because it predates the ban. Nothing in the law says which side pays. Buyers and sellers around here typically split it 50/50, so if your purchase contract is silent, assume you’re covering half. Claiming an exemption carries its own deadline tied to the recording date, and the county’s Department of Assessment and Taxation can tell you whether your transfer qualifies before you sign anything.
Who Pays HOA Fees at Closing in Oregon?
Before: a Lake Oswego seller believed her dues were current because autopay had been running for six years. After: escrow pulled the association’s statement and found two late fees and a special assessment for siding, all of it owed before she could convey clear title.
Dues get prorated. You own the property through closing day, so you pay the association’s monthly fee up to that date, and the buyer picks up everything after. If you’ve already paid the quarter in advance, you get credited back for the unused portion. The mechanical part is handled, and your escrow officer does the arithmetic.
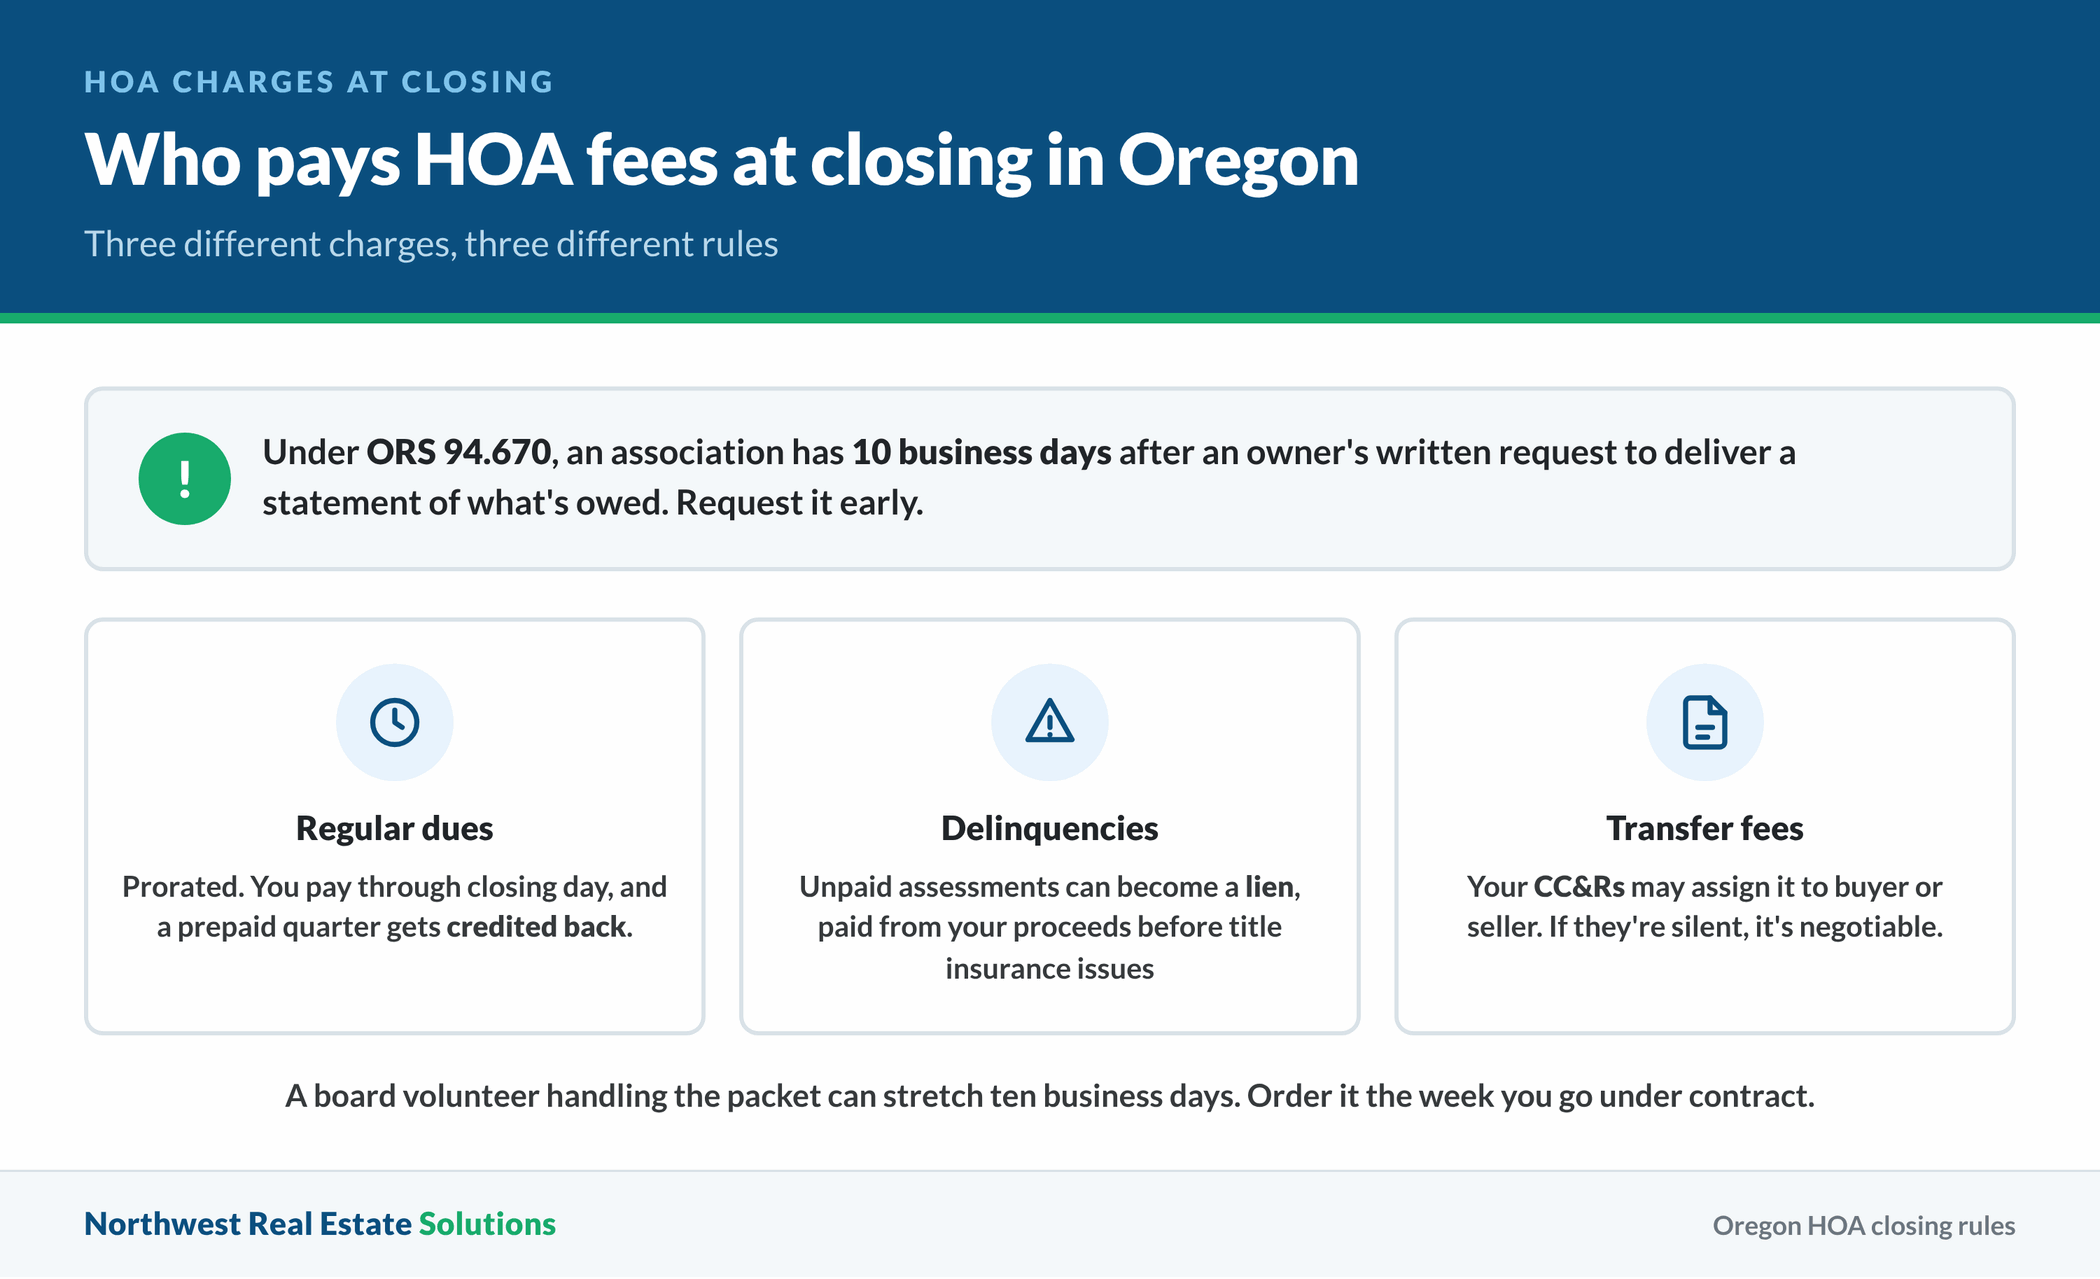
Delinquencies aren’t mechanical. Unpaid assessments can ripen into a lien against the property, and a lien has to be satisfied out of your proceeds before the buyer’s title insurance will issue. There’s no negotiating your way out of that one.
Transfer fees are a different animal. Plenty of Oregon associations charge a transfer or capital contribution fee when a lot changes hands, and the governing documents sometimes assign it to the buyer, sometimes to the seller, sometimes to nobody in particular. Read your CC&Rs. If they’re silent, it’s a negotiating point like anything else in the contract.
On written request from an owner, an association has ten business days to deliver a written statement of unpaid regular and special assessments, fines, interest, and late charges, along with the applicable interest and late-payment rates. That requirement comes straight from ORS 94.670. Request it early. When a board volunteer is handling it instead of a management company, ten business days can stretch, and a stalled packet is exactly the kind of thing we work around when we buy a house directly through Northwest Real Estate Solutions.
What Other Costs Could Cut Into Your Profit as an Oregon Seller?
You might figure that with no statewide transfer tax, selling here is cheap. Commissions fix that in a hurry.
Combined listing and buyer-side commissions in Oregon have commonly landed somewhere around four and a half to five and a half percent of the price, depending on your market and the service level you pick, and I’ve seen that range shift sale to sale. That single line dwarfs every other expense on the page. Everything else is a rounding error by comparison.
Property taxes get prorated the same way dues do, and your escrow officer calculates the split based on the county’s tax year rather than the calendar year. Your county’s assessment and taxation office can give you the exact current balance if you want to run numbers before listing.
Then there’s the repair column, which nobody forecasts correctly. Buyer’s agents in this state ask for repair credits as a reflex after inspection, and a roof or a crawlspace finding can swallow five figures. Add staging, photography, pre-listing cleaning, and the cost of carrying the house for another two months while it sits.
Capital gains can still bite you, depending on how the house was used. If the house was your primary residence for two of the last five years, the federal exclusion usually shields the gain entirely, though a rental conversion or an inherited property changes the math. A CPA earns their fee on that question.
What’s your actual walk-away number? The only figure that matters is rarely the one on the listing sheet.
What You Actually Pay, Heaviest First
I used to tell sellers the HOA stuff was minor. Then I watched a resale packet hold up a Tigard closing for eleven days, and I stopped saying it.
Stack these heaviest first, starting with whatever hits your wallet hardest. Agent commissions, if you’re listing. Your mortgage payoff, which isn’t a cost so much as a debt coming due. Any lien that shows up in the title search, including association assessments.
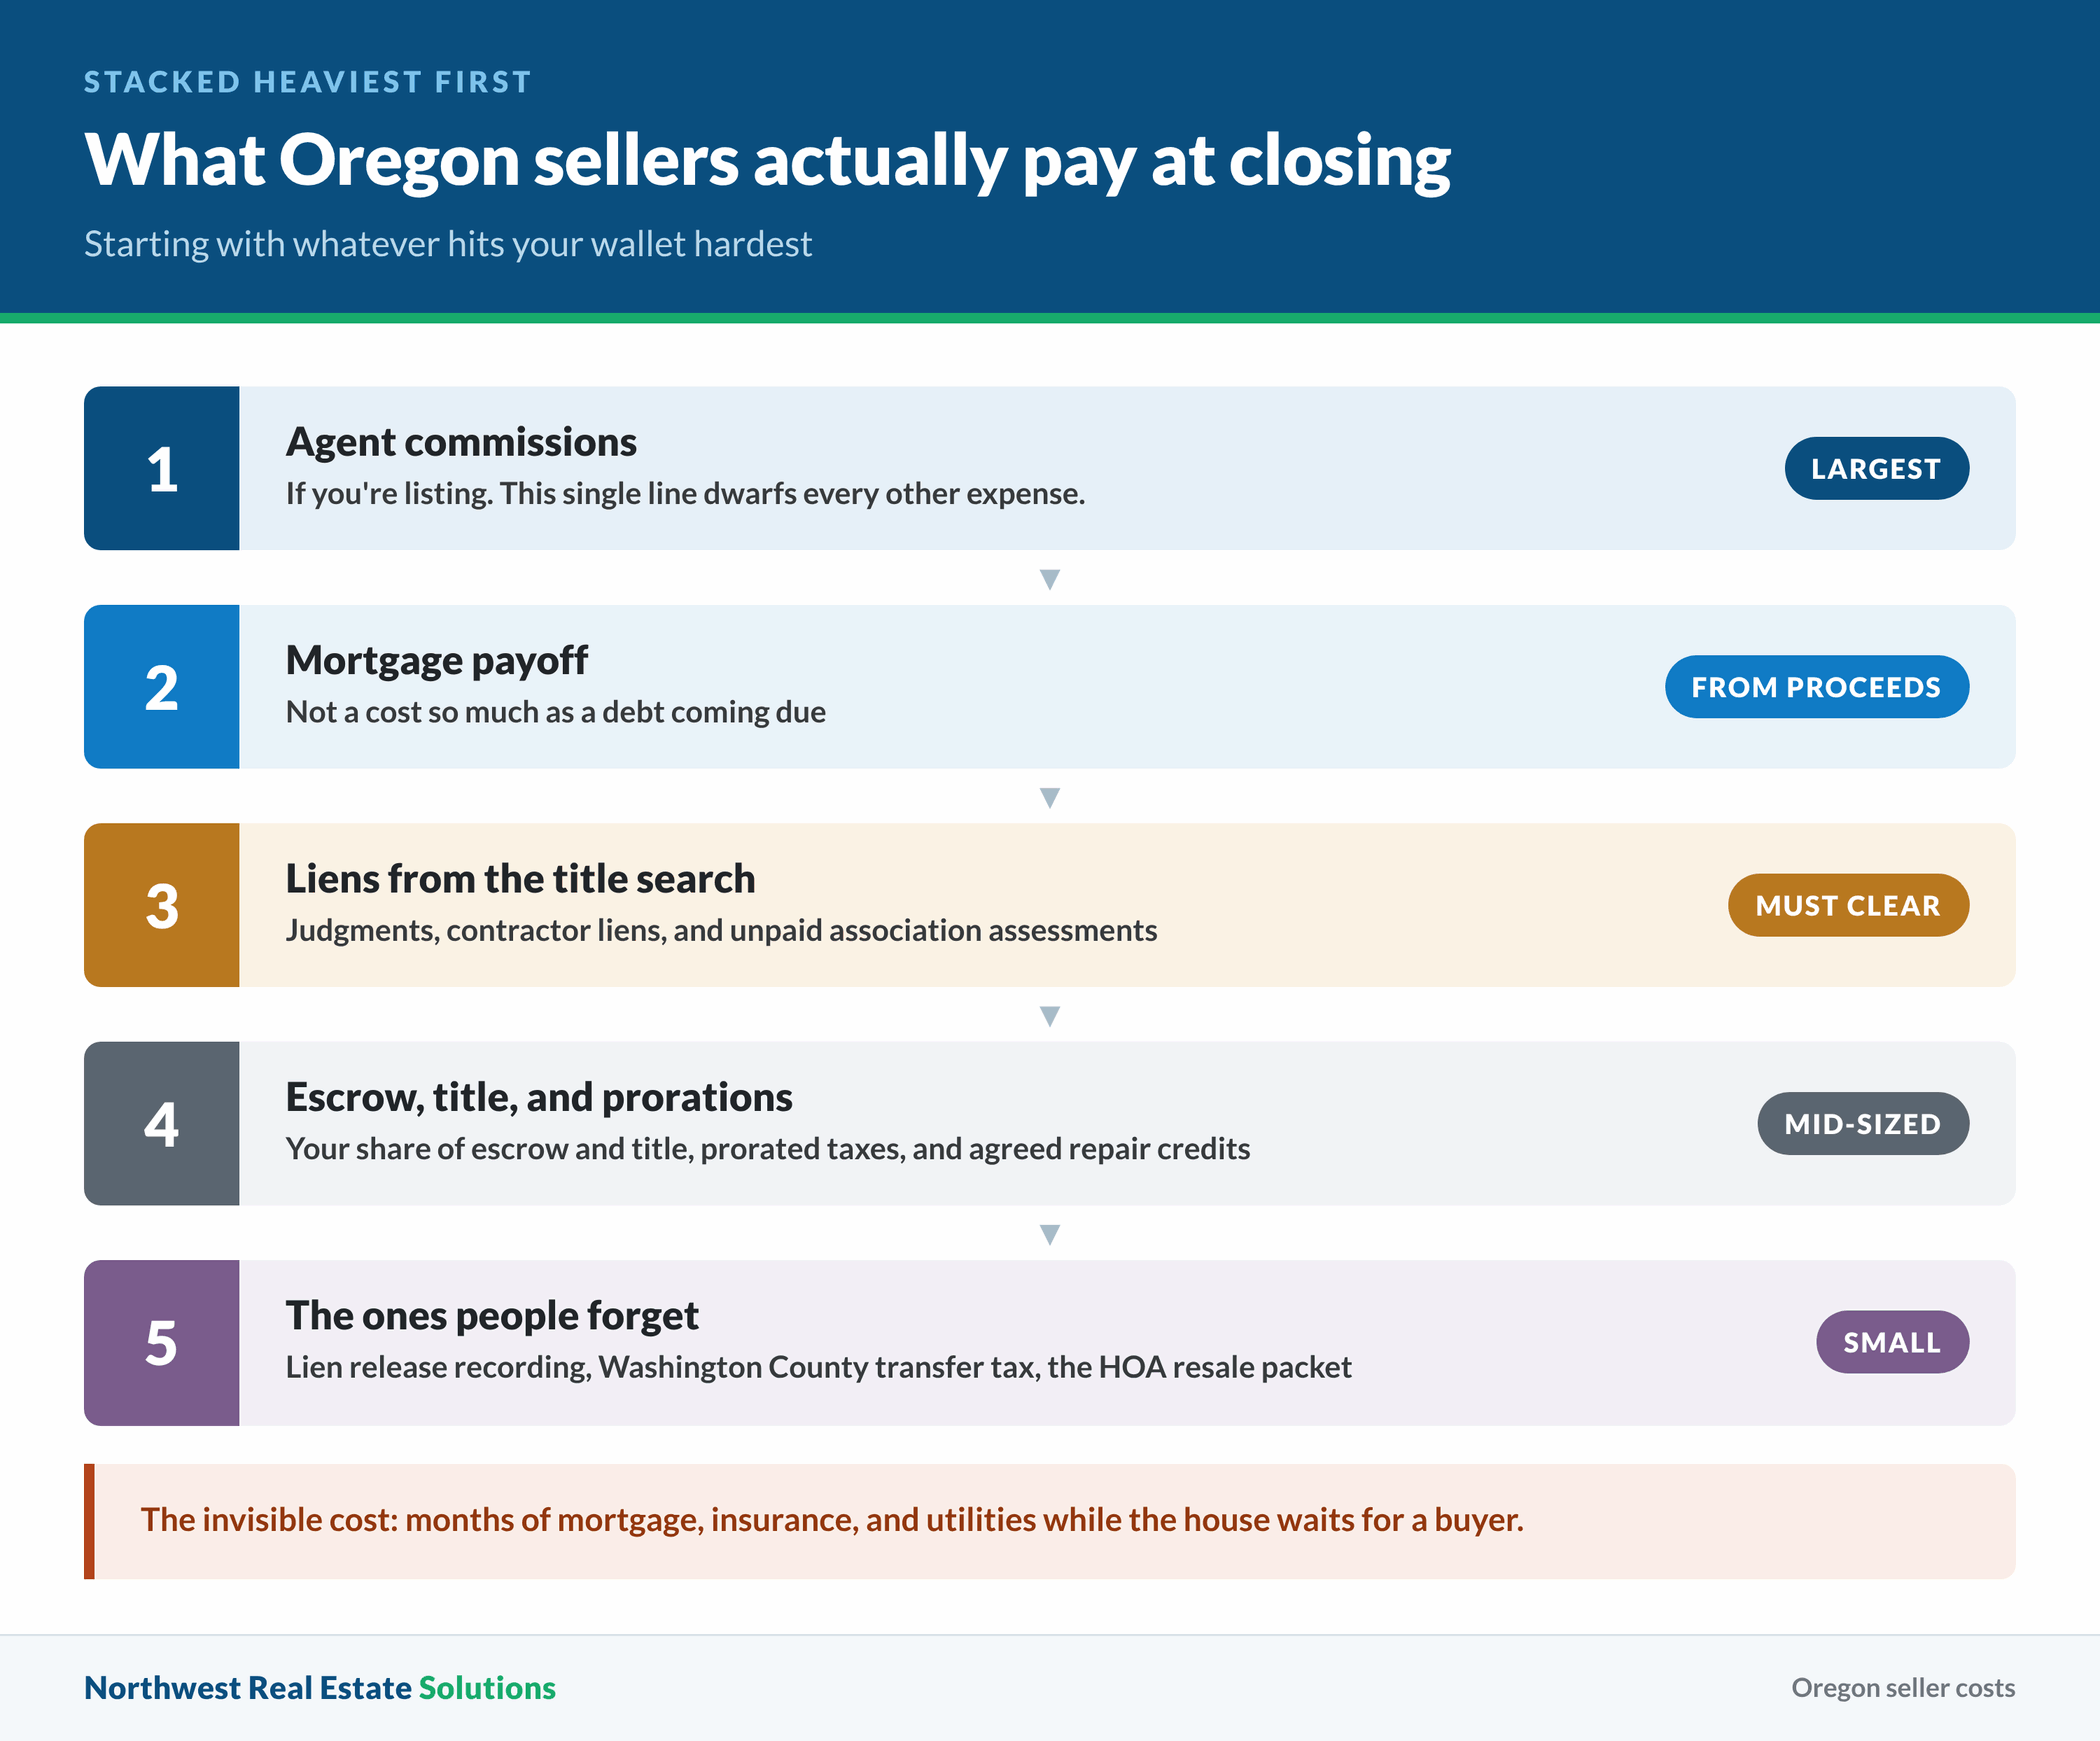
After that, the mid-sized items are your share of escrow and title charges, prorated property taxes, and repair credits you agreed to during the inspection period.
Near the bottom sit the ones people forget. Recording fees for lien releases. The Washington County transfer tax if your property’s inside that county line. The HOA’s charge for preparing the resale disclosure materials, which Oregon doesn’t cap the way Washington State does, so an association can bill what it costs them to produce.
And then the invisible cost nobody puts on a settlement statement: the months of mortgage payments, insurance premiums, and utilities you cover while the house waits for a buyer. That one’s real money.
How Much Are Closing Costs in Oregon?
Which brings us to the number everyone wants up front. Add up commissions, title, escrow, prorations, and the small recording charges, and most Oregon sellers give up somewhere between six and ten percent of the sale price. Commissions eat the lion’s share of it, which lines up with what I’ve seen on every closing I’ve been part of.
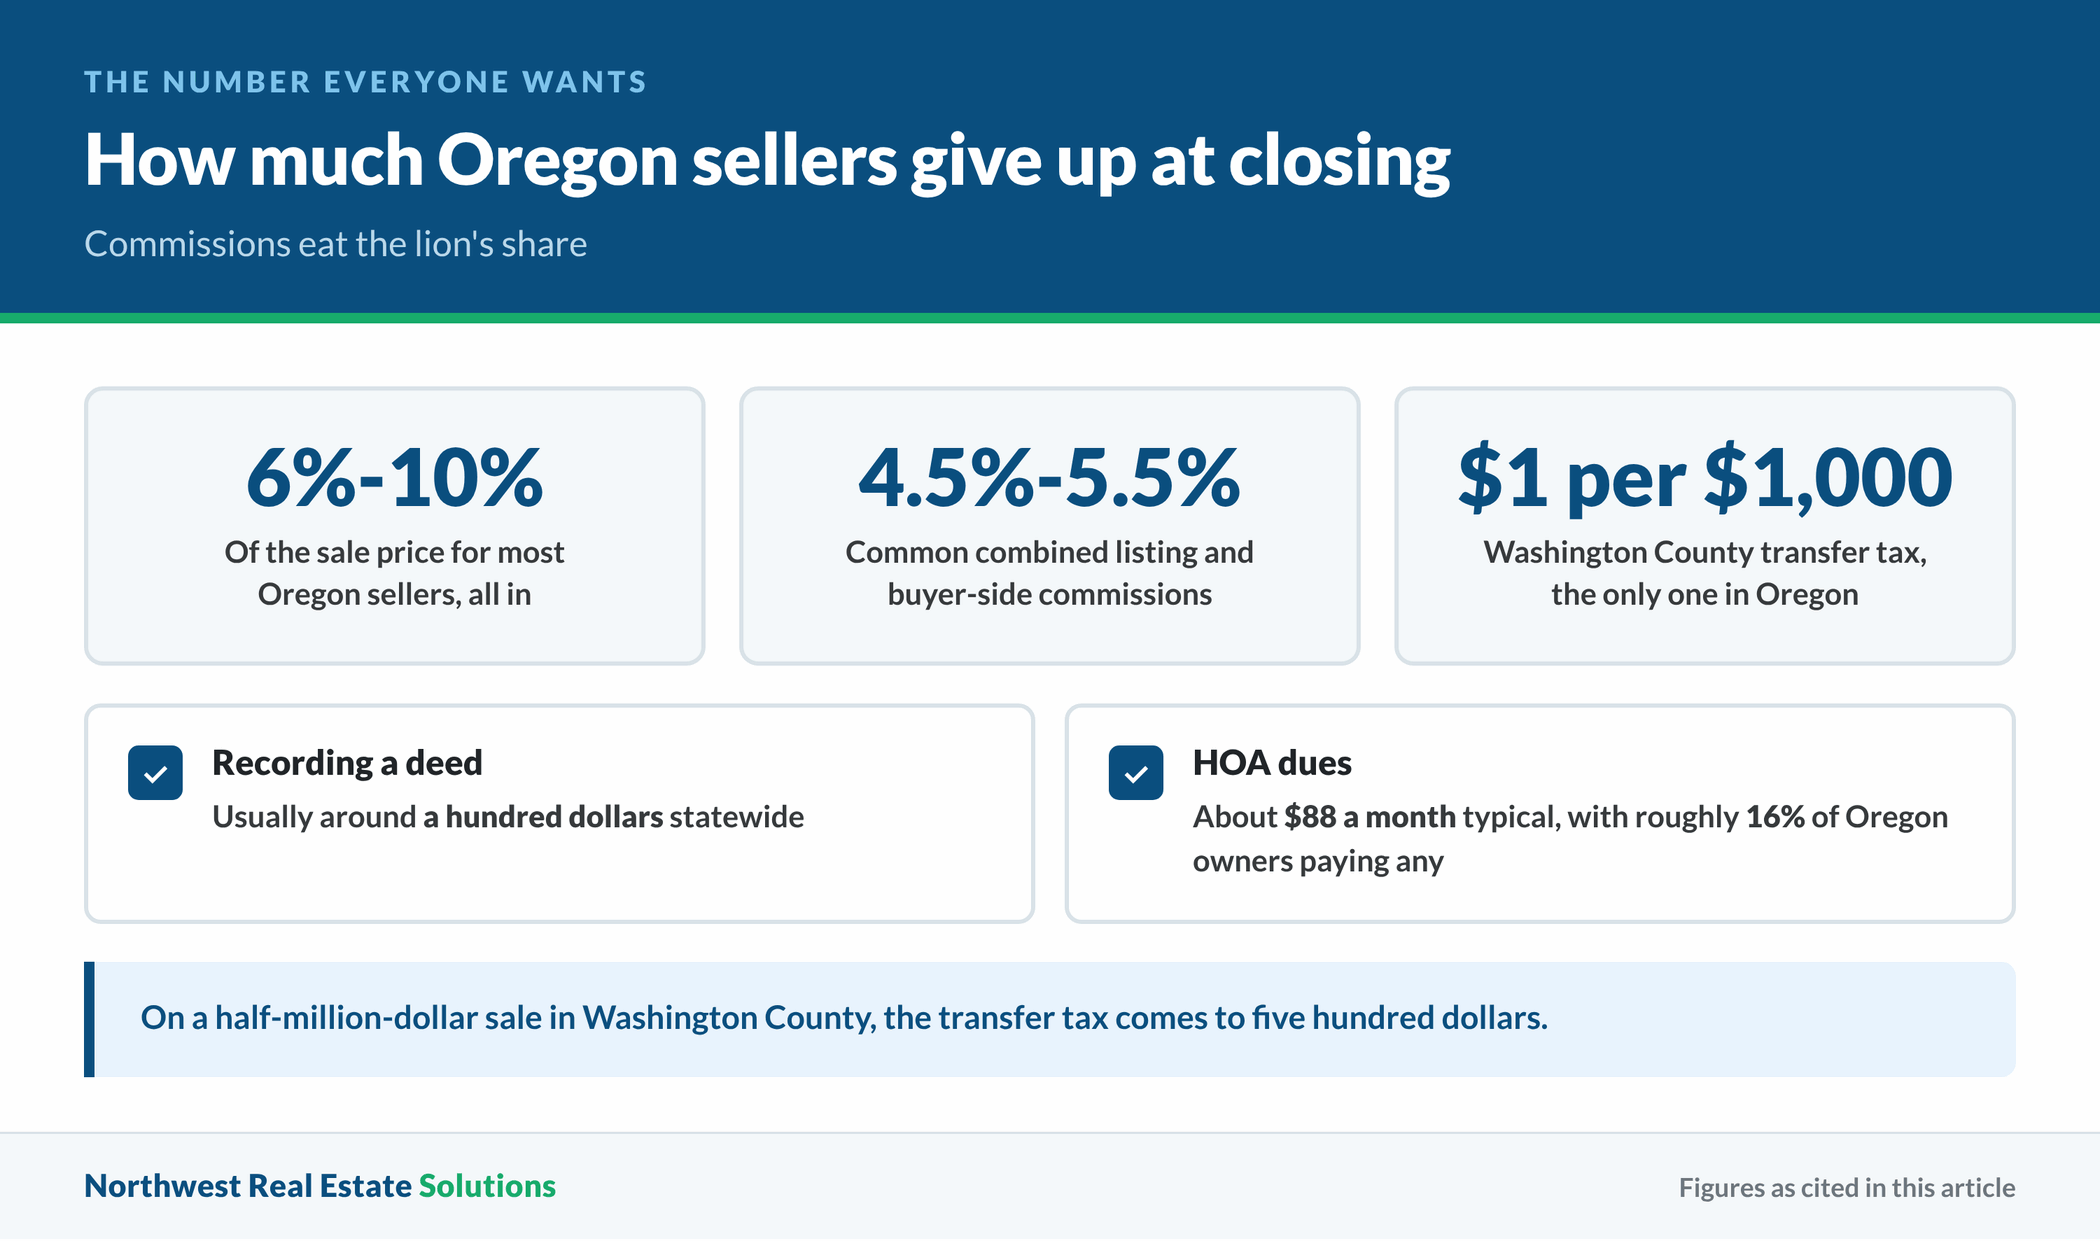
Run that against a typical Oregon house and you’re looking at roughly thirty to fifty thousand dollars evaporating between the accepted offer and the wire hitting your account. This is before any repair credit you negotiated.
Buyers have their own column: loan origination, appraisal, lender’s title insurance premium, prepaid interest, and their portion of escrow. Their total typically runs lower than yours because they’re not paying commission.
People credit timing less than it matters. Homes across Oregon spent a median of 39 days on market in August 2026, and closing adds another month on top of that. Every one of those days is another day of mortgage interest, property insurance, and lawn care on a house you’re trying to leave.
Sellers working with us through Northwest Real Estate Solutions skip the commission line altogether, which changes the arithmetic more than any other single decision. It’s not right for everyone. If your house shows beautifully and you’ve got time, the open market will usually net you more.
What Affects Closing Costs in Oregon?
In Eugene, the median home price hit $520,000 in September 2026, with houses averaging 45 days on market and selling at 99.4 percent of asking, per local MLS tracking from Lane County. I’ve seen this firsthand buying in both markets, and a seller there and a seller in Burns face wildly different dollar amounts for identical percentage-based fees.
Price drives most of it. Commission is a percentage. Title insurance premiums scale with the policy amount. The Washington County tax scales with the sale price. Only the flat fees stay flat.
Property type swings the HOA side hard. Census-based figures reported in 2026 put the typical Oregon homeowner’s association payment at about $88 a month, with roughly 16 percent of owners in the state paying any dues at all, according to iPropertyManagement’s research. The median hides enormous spread. Reported Oregon fees run from fifty dollars to north of two thousand, and a Pearl District condo with an elevator, a doorman, and a reserve-funded roof lives at the top of that range.
Negotiating leverage shifts the rest. In a market where inventory’s tight, sellers push closing costs onto buyers. When listings stack up and price cuts spread, buyers ask for credits and get them.
Condition is the quiet variable. A deferred-maintenance house attracts offers with longer repair addenda, and every item on that addendum is a cost you either pay or lose the sale over.
Can the Seller Pay the Buyer’s Closing Costs in Oregon?
Yes, and sometimes you should, even though it feels backward.
Seller concessions are written into the purchase contract as a credit, usually a fixed dollar amount or a percentage of the price. Escrow applies it against the buyer’s loan costs at settlement. Lenders impose caps based on the loan type and down payment, so your buyer’s loan officer has to sign off before anyone celebrates.
The strategy works because buyers are cash-constrained, not price-constrained. Somebody who scraped together a down payment often can’t find another eight thousand dollars for closing. Offering a credit instead of a price reduction keeps your sale price on the comps and solves their real problem. I’ve seen that trade save sales that a straight price cut wouldn’t have.
Sellers often agree to a credit without checking the appraisal risk first, and that’s where things go wrong. Bump the price to cover the concession, and the house has to be appraised at the higher number. If it doesn’t, you’re renegotiating anyway, except now you’ve burned three weeks.
You can also refuse. Nothing obligates you to cover a buyer’s expenses. Just understand what refusing costs you in a market where the median Oregon listing isn’t selling in a weekend anymore.
Who Pays for Title Insurance and Escrow Fees in Oregon?
In Oregon, sellers generally cover the owner’s title insurance policy. You’re guaranteeing the buyer receives clear ownership, so you buy the policy that backs that promise. The buyer usually purchases the lender’s policy separately, since their mortgage company demands it.
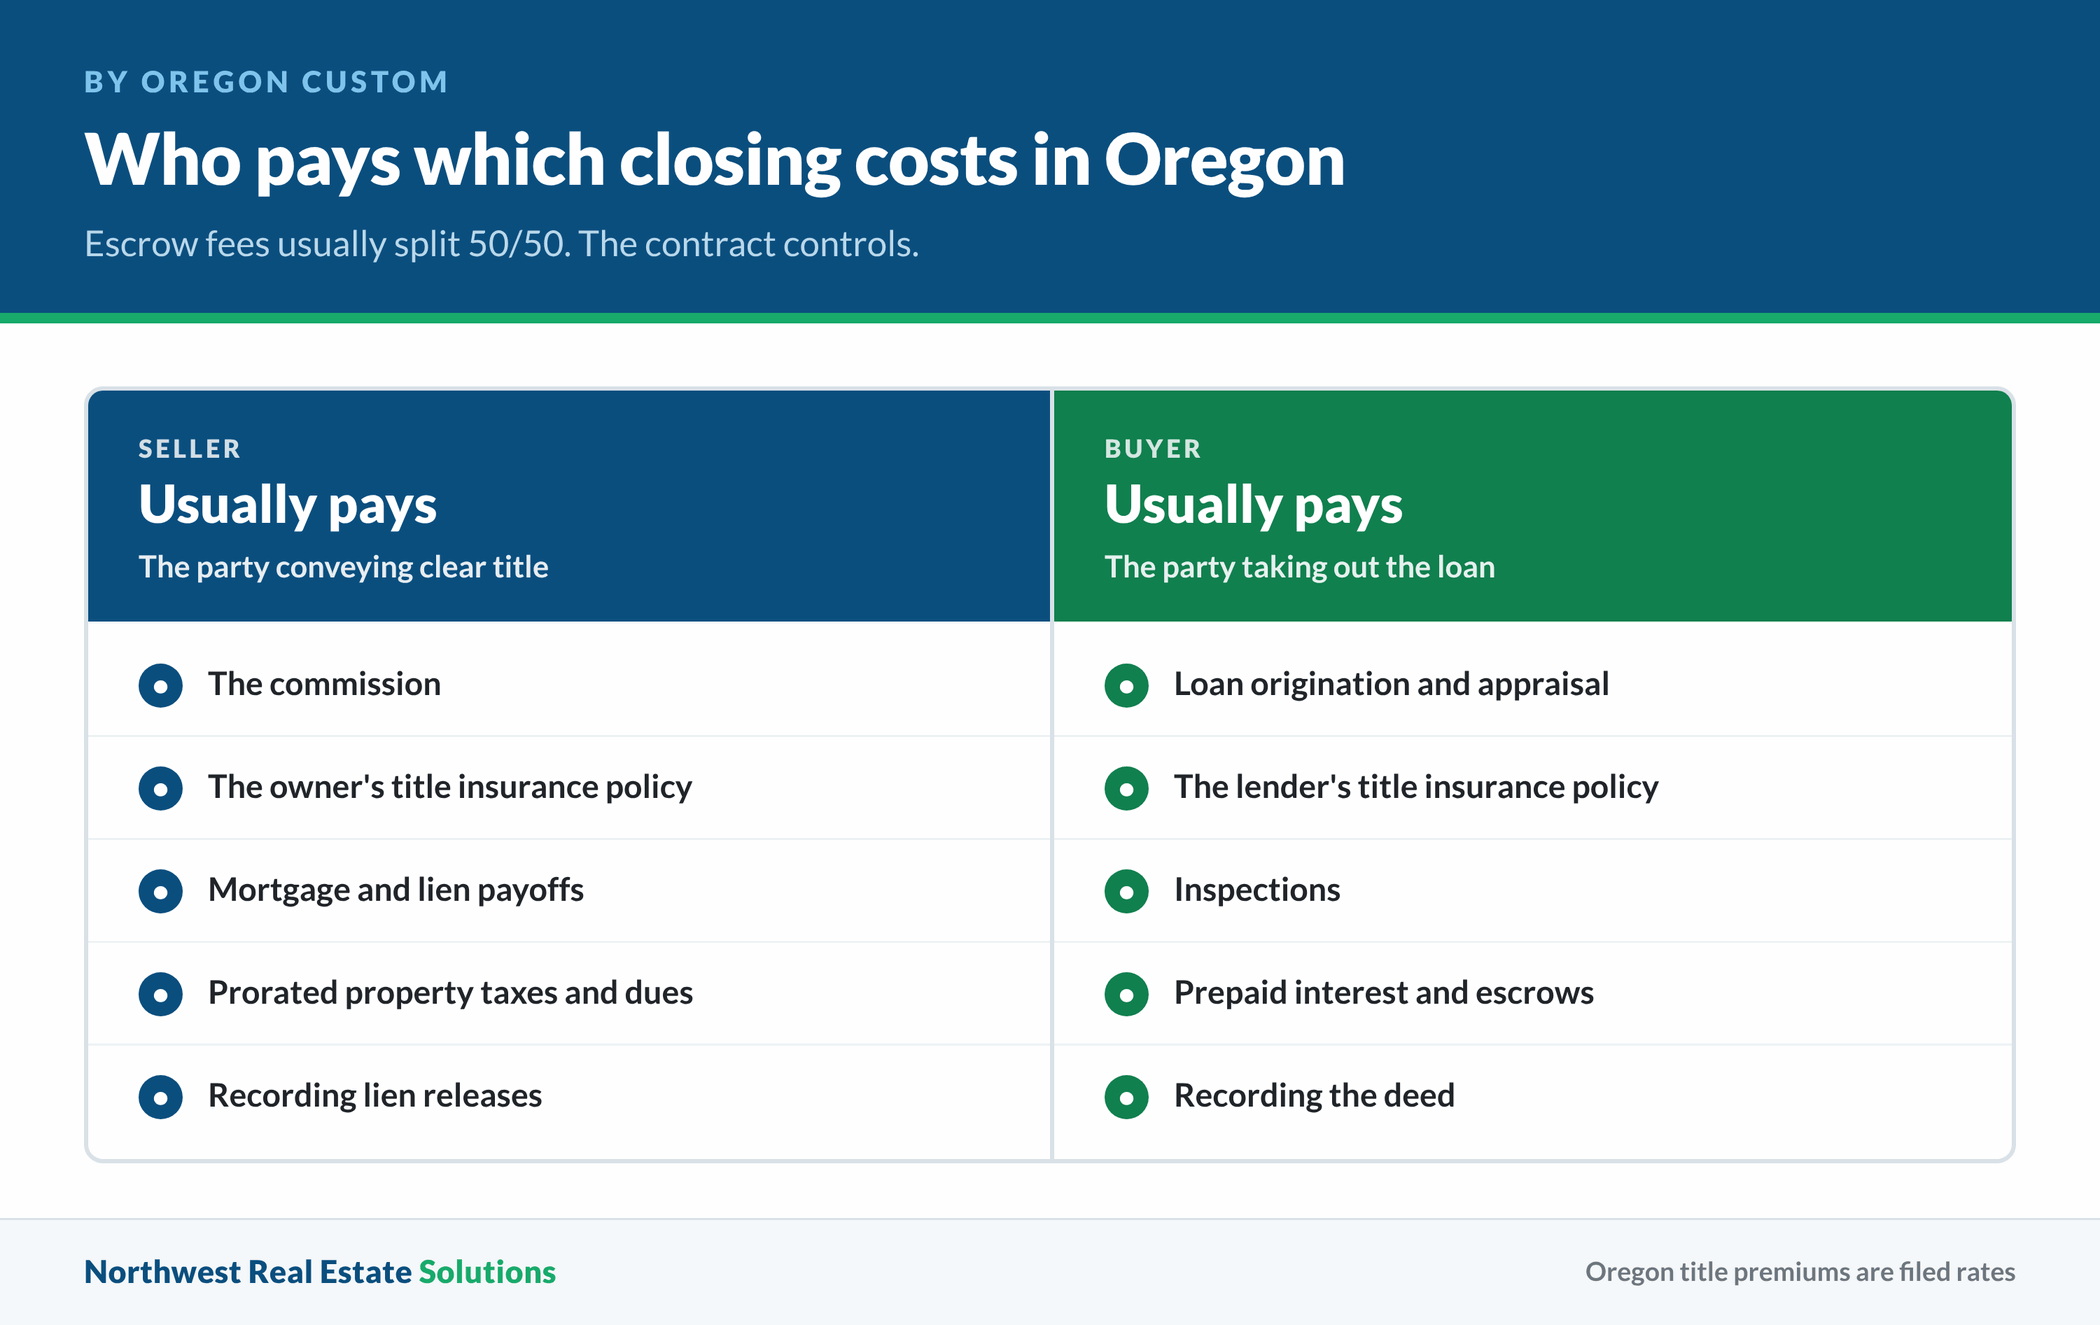
Escrow fees get split. Most Oregon transactions divide the escrow agent’s charge 50/50 between both parties, though the contract controls, and either side can offer to absorb the whole thing as a negotiating chip. Your escrow company publishes a rate card; ask for it before you sign.
Here’s something worth knowing. Title insurance premiums in Oregon are filed rates, so shopping around saves less than you’d hope. Service quality is the real differentiator, and a title officer who answers the phone is worth more than a forty-dollar discount.
Frequently Asked Questions
Who Covers the Cost of the HOA Closing Letter?
Oregon doesn’t assign this one by statute, so it comes down to your purchase contract and the association’s own rules. Common practice puts it on the seller, because you’re the party who has to prove your account is current. Ask your escrow officer to order it the week you go under contract rather than the week before closing.
Who Normally Pays Closing Costs When Selling in Oregon?
Both sides pay, but not evenly. Sellers carry the commission, the owner’s title policy, their lien payoffs, and prorated amounts for property taxes. Buyers carry loan origination, appraisal, inspections, their lender’s title policy, and their own prepaid escrows. The split lands somewhere between six and ten percent of the sale price on the seller’s side once commission is included.
Does Oregon Charge a Real Estate Transfer Tax?
Only Washington County does, and it’s limited to one dollar per thousand of the sale price. Every other county in the state is barred from imposing one under a 1997 law. So on a $450,000 Beaverton sale, you’re looking at $450, usually split 50/50 between buyer and seller unless the contract says otherwise. Everywhere else in Oregon, the line item simply doesn’t exist.
Can I Sell If I Owe More Than the House Is Worth?
Yes, but the path changes. You either bring cash to closing to cover the gap, or you ask your lender to approve a short sale. Short sales take longer and require documentation of hardship, and the lender controls the timeline. If you’re also behind on payments, get the payoff figure in writing before you list so you know which conversation you’re actually having. It also helps to check how much equity you need to sell your house in Oregon before you decide.
How Soon Do I Get My Money After Closing?
In Oregon, recording usually happens the same day or the next business day, and escrow disburses once the county confirms it. Wire transfers land within a day of disbursement. Plan on two to four business days from signing to funds in your account, longer if you sign on a Friday.
We Buy Houses in Portland and Across Oregon, HOA or Not
Portland is our home market, and plenty of the condos and townhomes we see there come with association dues and a resale packet attached. RMLS reported 1,902 closed sales across the Portland metro in August 2026, down 5.9 percent from a year earlier. Fewer closings means more sellers waiting on buyers while the dues keep coming.
We’re cash home buyers in Portland, and we buy houses across the metro and the rest of the state. Southwest of the city, we buy houses in Tigard. Down the valley, we’re investor home buyers in Salem. You can see every area on our “We Buy Houses in Oregon” page.
Sell Your Oregon Home Without Chasing the HOA Packet
Closing costs aren’t the thing that sinks a sale. Surprises are. If you know your payoff, your prorated taxes, and roughly what the commission will run, you can look at any offer and tell within a minute whether it works for you.
If your situation has a deadline attached, an auction date, a probate deadline, or a job that starts in another state, it’s worth knowing what a direct sale would net you before you commit to the traditional route. No obligation, no pressure, just a number you can compare against. Reach out when you’re ready to see it.
When we buy a house directly, we cover the standard closing costs, and there’s no commission on either side. The escrow company still orders the association statement, and any past-due dues or assessments come out of your proceeds at closing, so there’s nothing for you to chase. We’ll give you a cash offer in writing so you can compare it with your net from a listing.
Have more questions first? Check out other frequent questions. When you’re ready, fill out our quick contact us form or use the short form below.
Helpful Oregon Blog Articles
- Who Is Responsible For HOA Fees At Closing In Oregon
- Guide To Oregon Inheritance Laws
- Paperwork For Selling Your Oregon Home by Owner
- Understanding Squatters’ Rights In Oregon Real Estate
- How To File A Quitclaim Deed For Real Estate In Oregon
- Homeowners Insurance When Selling a House in Oregon
- Can You Sell a House with Asbestos in Oregon
- How to Sell a House with Mold in Oregon
- Can the Seller Back Out of a Contract in Oregon?
- How Much Equity Do I Need to Sell My House in Oregon?
- Taxes When Selling an Inherited House in Oregon
- Do Open Houses Still Work When Selling a Home in Oregon?
- How to Sell a House with Flood Damage in Oregon