
Rain in the Coast Range never stays where it lands. It runs down the Nehalem, the Santiam, and the Tualatin, and sometime around two in the morning in February, it finds a crawlspace vent in somebody’s rancher. By breakfast, that homeowner owns a different house than the one they bought.
Selling a flood-damaged property here works differently than selling a clean three-bedroom near a good elementary school. Buyers get jumpy. Lenders tighten up. The disclosure form asks questions you can’t talk your way around. Yet water-damaged houses trade hands in this state every single month, and a lot of them close for more than the asking price.
What follows is how the process really runs, what it costs, and where sellers quietly leave money behind.
What Oregon Home Buyers Want to Know About Flood Damage
For years I assumed the first thing a buyer asked about a flooded house was how deep the water got.
It isn’t. They want to know whether it comes back, and they want to know who paid for the cleanup the first time around. Depth is a story. Recurrence is a risk, and risk is what a buyer is pricing.
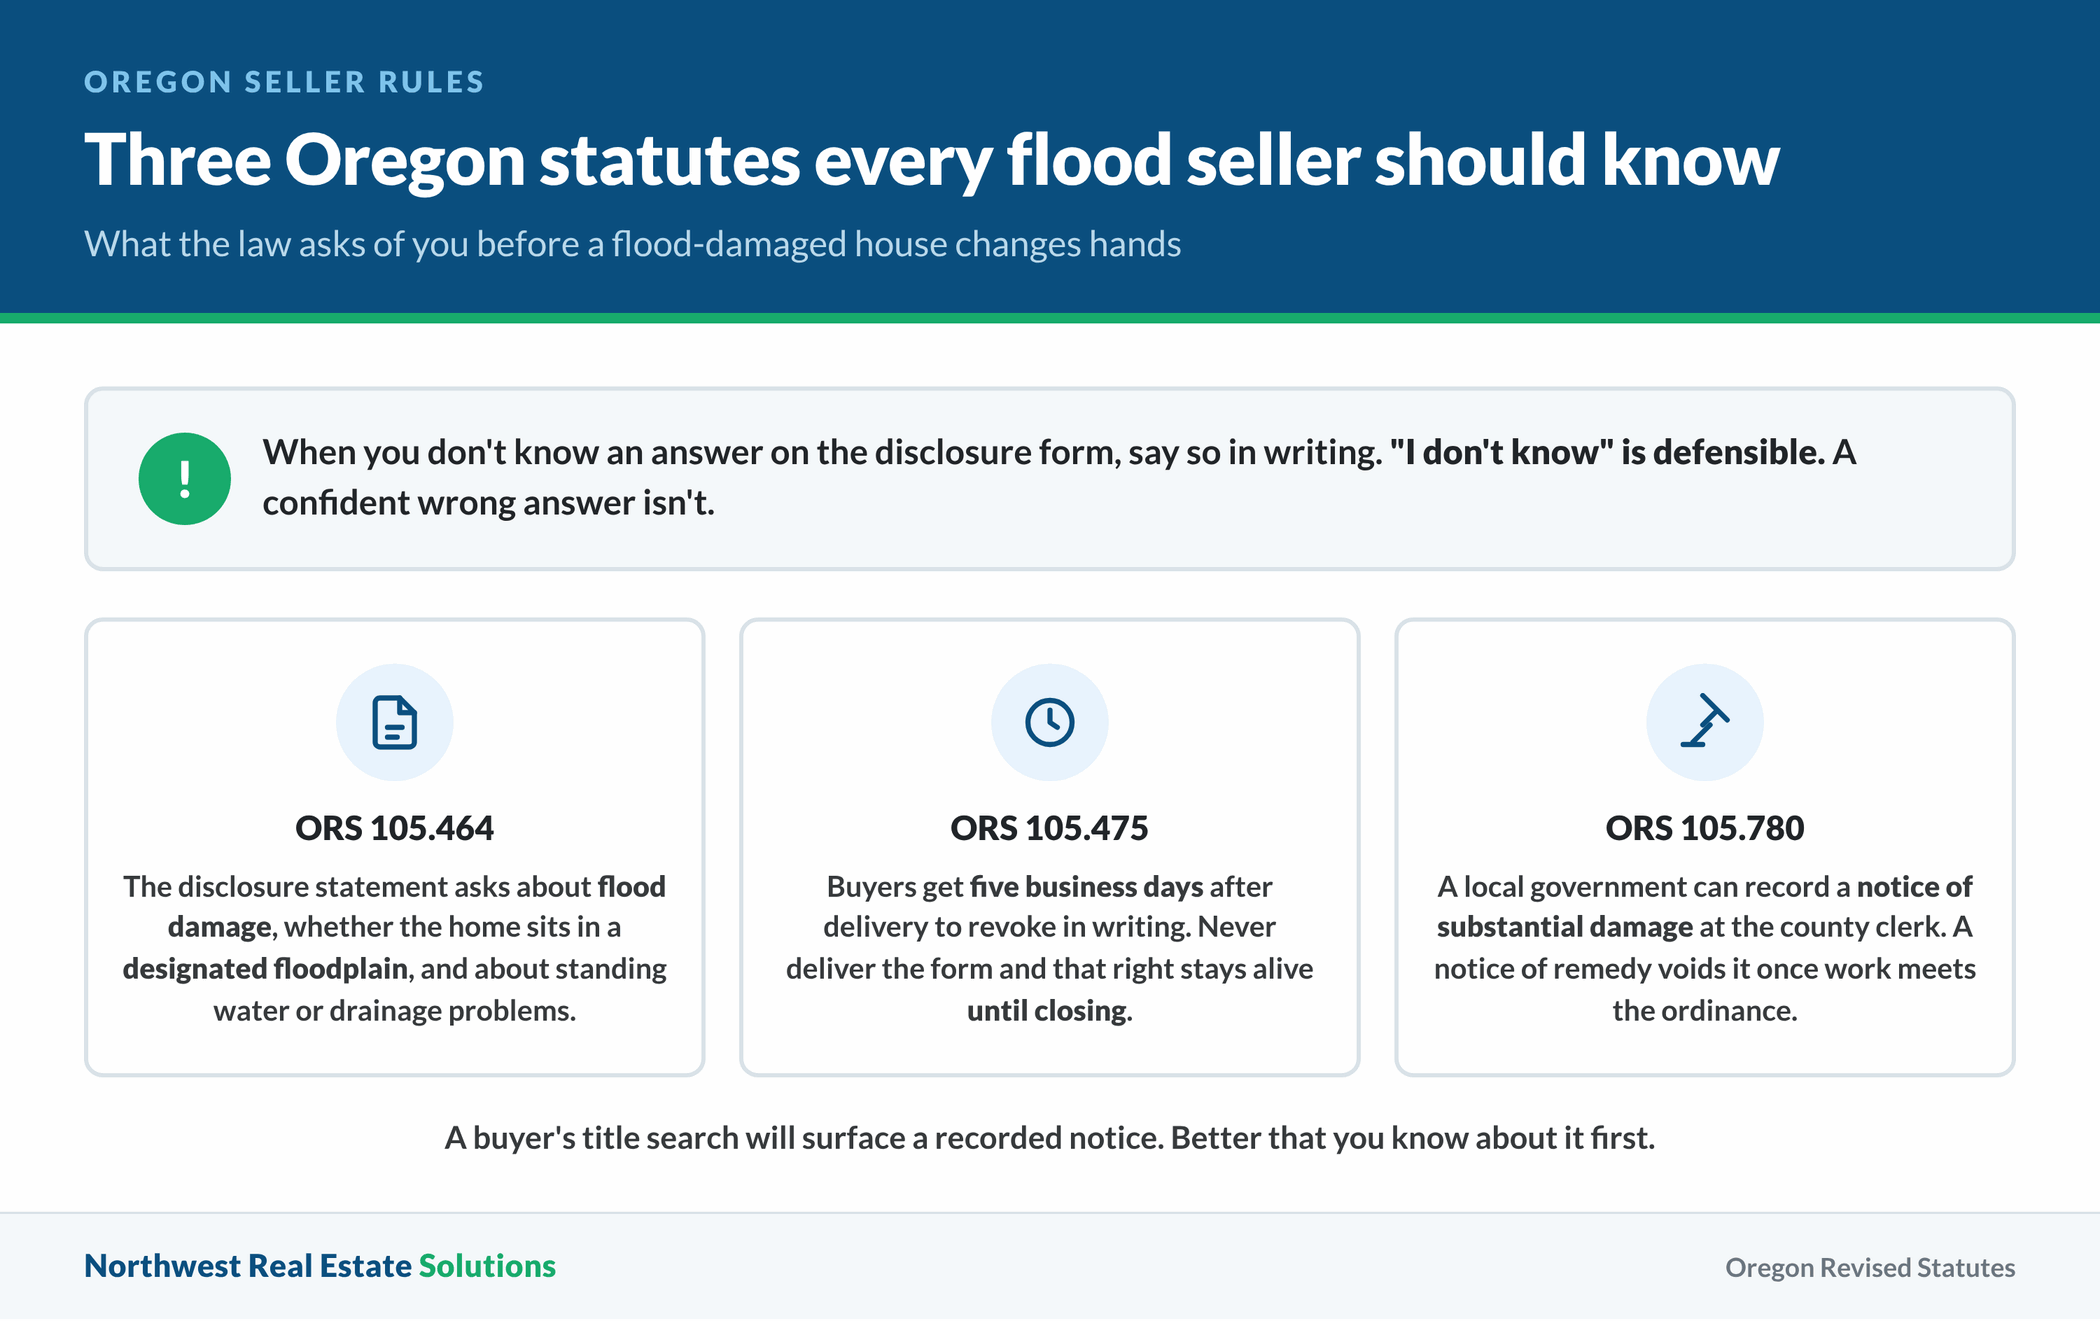
Oregon hands them a tool for digging into both. The seller’s property disclosure statement, the form laid out in ORS 105.464, asks directly whether any structure has material damage from fire, wind, floods, beach movements, earthquake, or landslides. Another line asks if the property sits in a designated floodplain, while a separate question covers standing water and drainage problems on the land itself.
Answering those honestly is not optional, and softening the answers is the single most expensive mistake I see sellers make. When you genuinely don’t know the answer to one of them, say that in writing instead of guessing in either direction. “I don’t know” is a defensible position. A confident wrong answer isn’t.
A clock is attached, too. Under ORS 105.475, a buyer who hasn’t waived the right gets five business days after the disclosure statement is delivered to revoke the offer in writing and take back the earnest money. Business days, not calendar days. A seller who never delivers the form at all doesn’t lose that revocation right; the statute keeps it alive until the transaction closes. Sellers who think silence buys them safety have it backwards.
Then there’s the county record. A local government with land use jurisdiction can record a notice of designation of substantial damage at the county clerk’s office when a home took substantial damage from flooding, as defined in that jurisdiction’s hazard ordinance, and hasn’t been brought back into compliance. That authority sits in ORS 105.780, and the same statute lets the local government record a notice of remedy that voids the designation once the work meets the ordinance. A buyer’s title search will surface it. Better that you know about it first.
Insurance is the other half of the conversation. Standard homeowners policies in Oregon don’t cover flood, a point the state’s Division of Financial Regulation makes without hedging, so coverage has to come from the National Flood Insurance Program or a private insurer. Roughly 22,030 NFIP policies were in force across Oregon during the twelve months ending August 31, 2026, at an average premium near $954 a year. Federal residential coverage caps out at $250,000 on the building and $100,000 on contents. Fire is another story, since standard home policies usually cover it, which is one reason selling a fire-damaged house in Portland, OR runs differently than a flood sale.
Do the arithmetic from the buyer’s chair for a second. Portland’s median sale price sat at about $518,000 over the three months ending September 2026, down 2.2% year over year, with the typical home going pending in 25 days. A federal policy ceiling well under that median is exactly why a cautious buyer starts asking about elevation certificates and past claims.
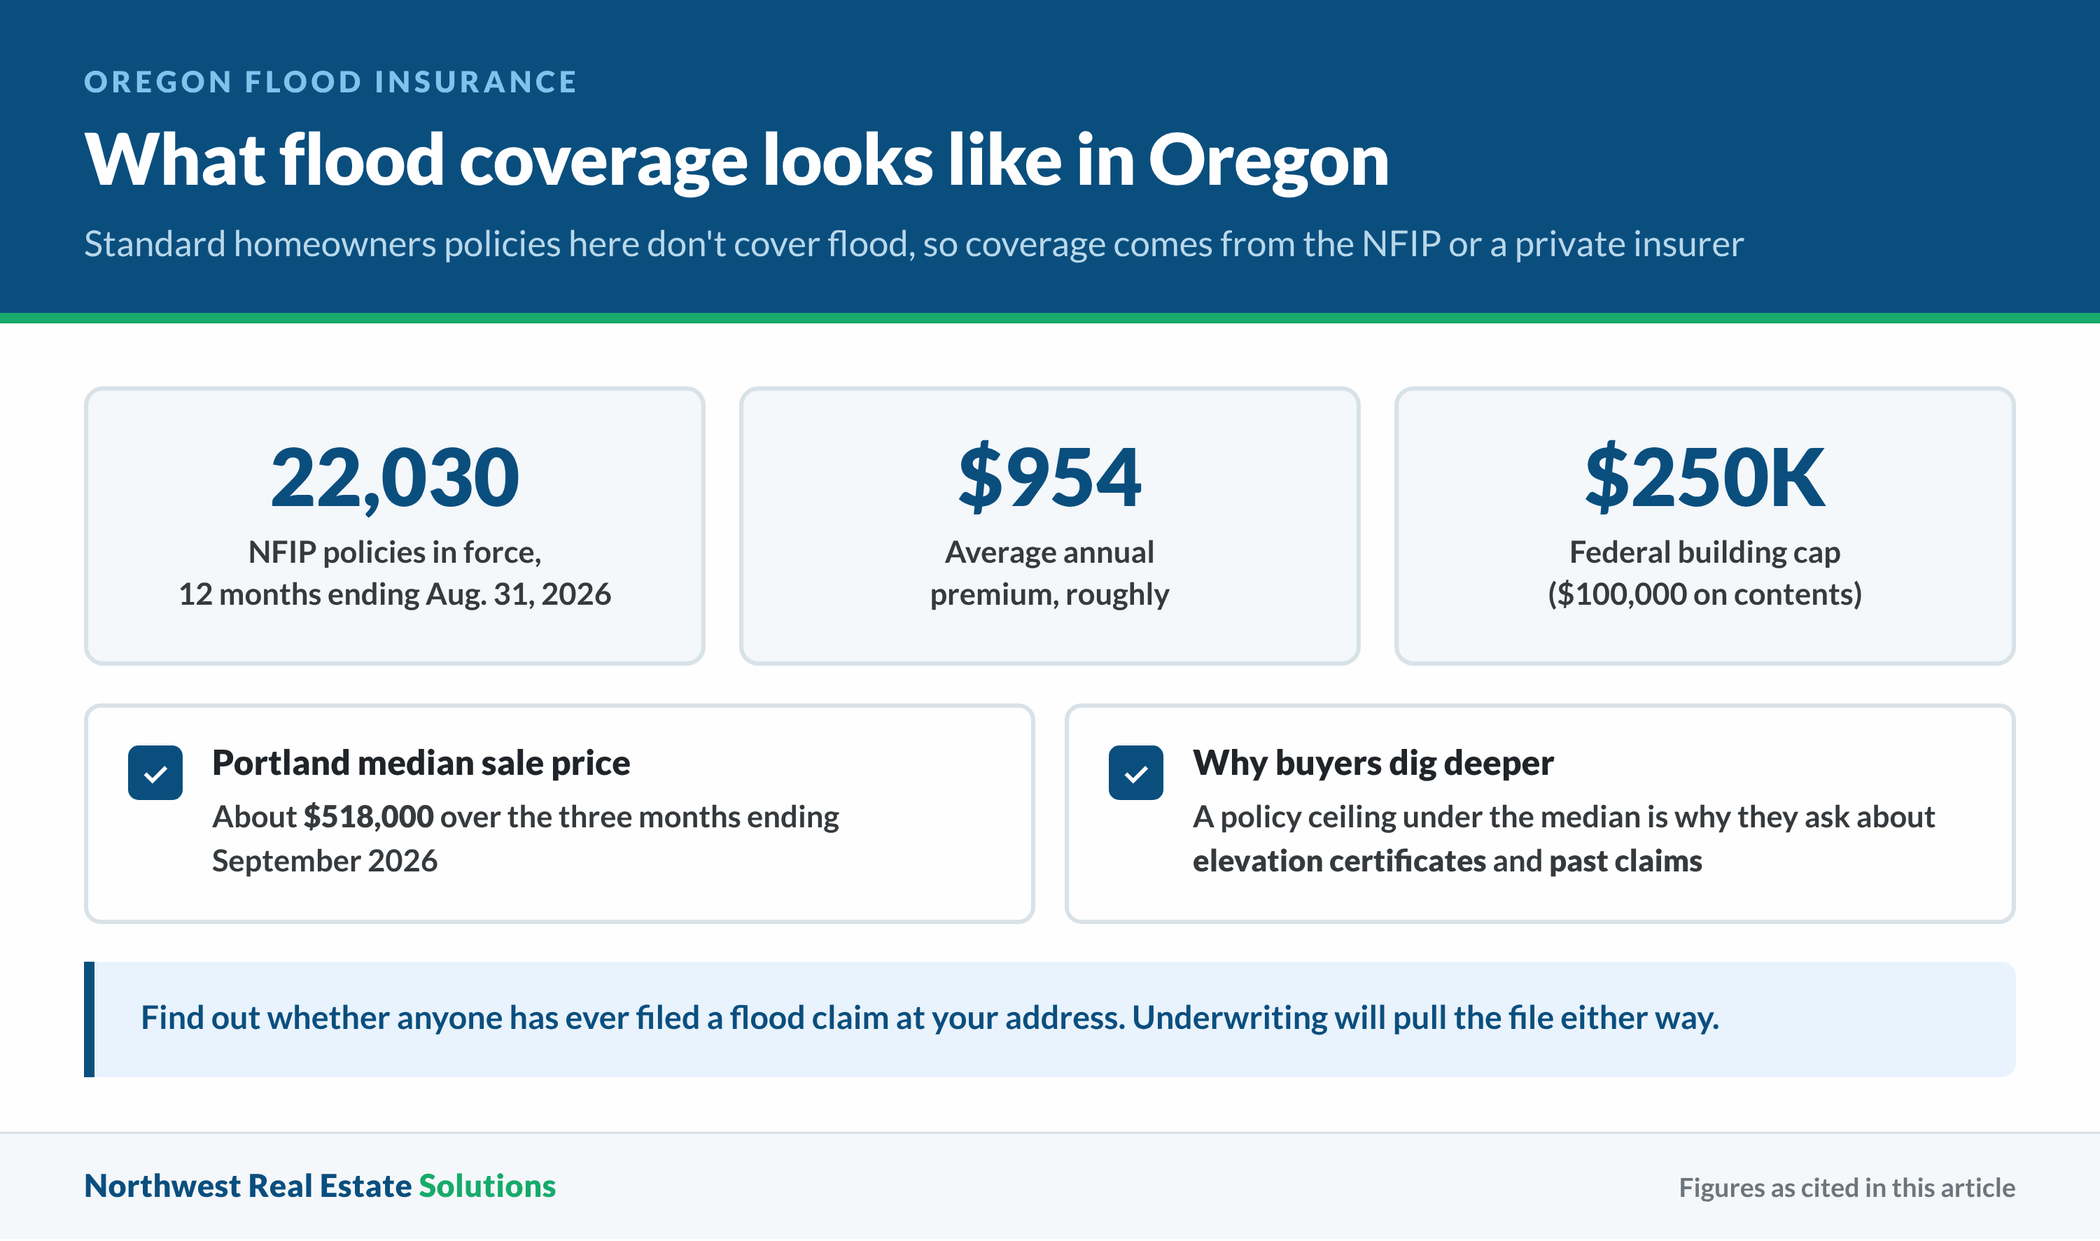
Find out whether anyone has ever filed a flood claim at your address.
Your insurance company can pull the loss history, and a buyer’s agent can order a claims report just as easily. Pretending a prior claim doesn’t exist works until underwriting pulls the file, which is usually day nine of escrow. Mold is the third rail here. Water that sat behind baseboards for a week grows something, and a buyer who smells it in the hallway stops caring about your granite.
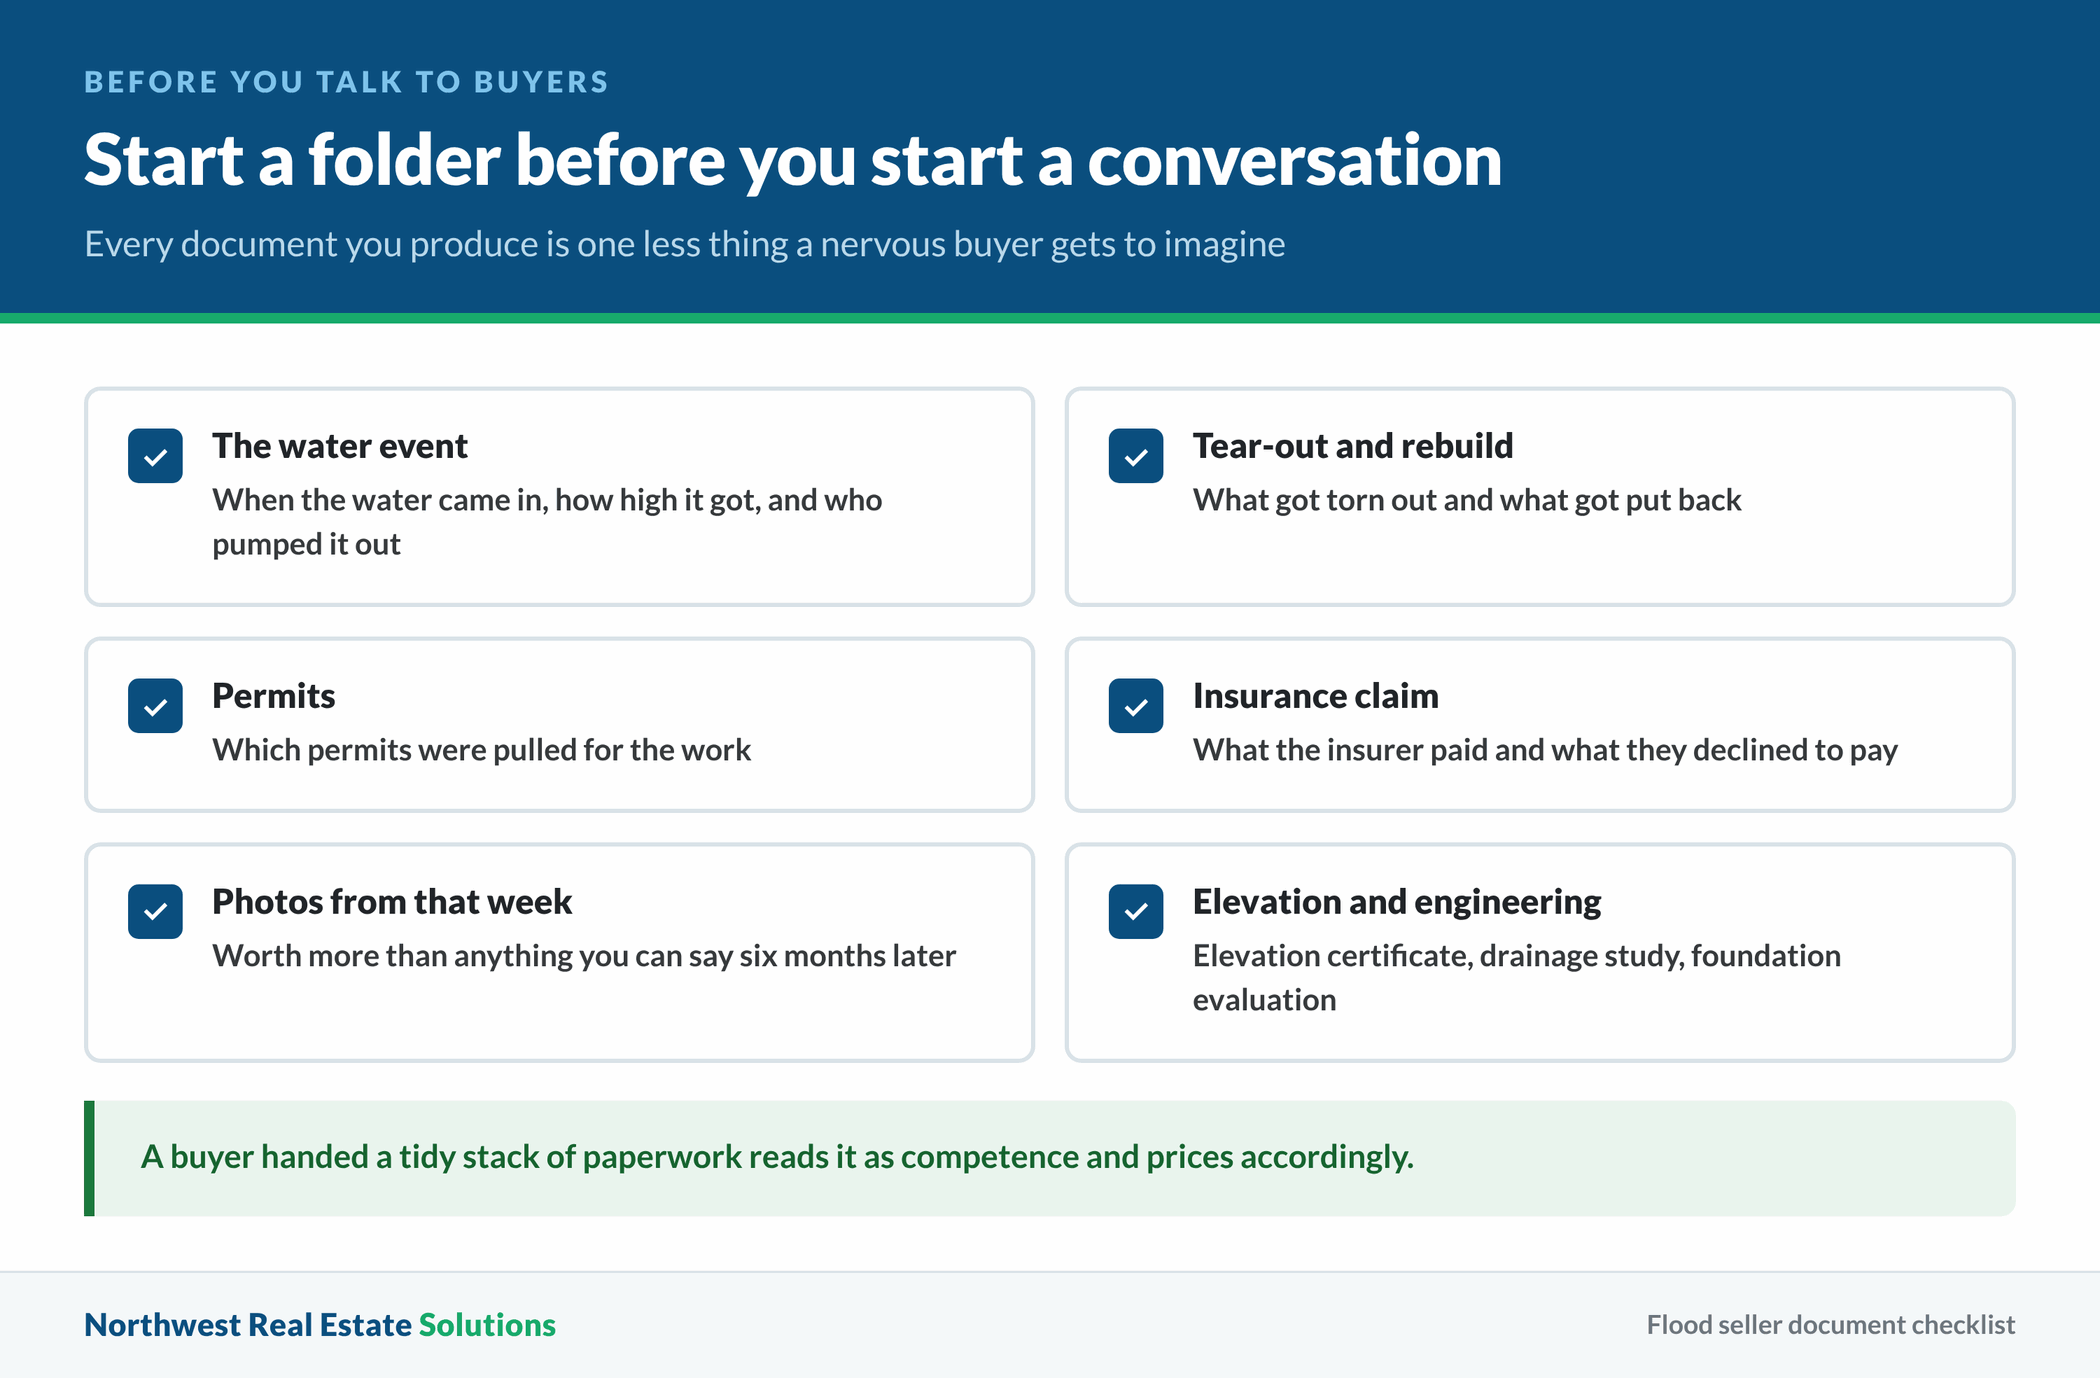
Start a folder before you start a conversation. When the water came in, how high it got, who pumped it out, what got torn out and what got put back, which permits were pulled, what the insurer paid, and what they declined to pay. Photos from the week it happened are worth more than anything you can say out loud six months later, something I’ve learned the hard way buying houses with gaps in the paper trail. A buyer handed a tidy stack of paperwork, read it as competence, and priced accordingly. A buyer handed shrugs fills in the blanks himself, and the blanks he invents are always worse than what actually happened.
If an elevation certificate exists for the property, dig it up now. If one doesn’t, understand that a buyer shopping for flood coverage may want one, that it takes a surveyor, and that ordering it costs you lead time you’d rather spend in escrow. The same goes for any engineering report, drainage study, or foundation evaluation sitting in a drawer. Every document you produce is one less thing a nervous buyer gets to imagine.
Can You Sell an Oregon Home As-is Without Repairs?
You can sell this house exactly as it sits, and nobody on earth can make you cut drywall first.
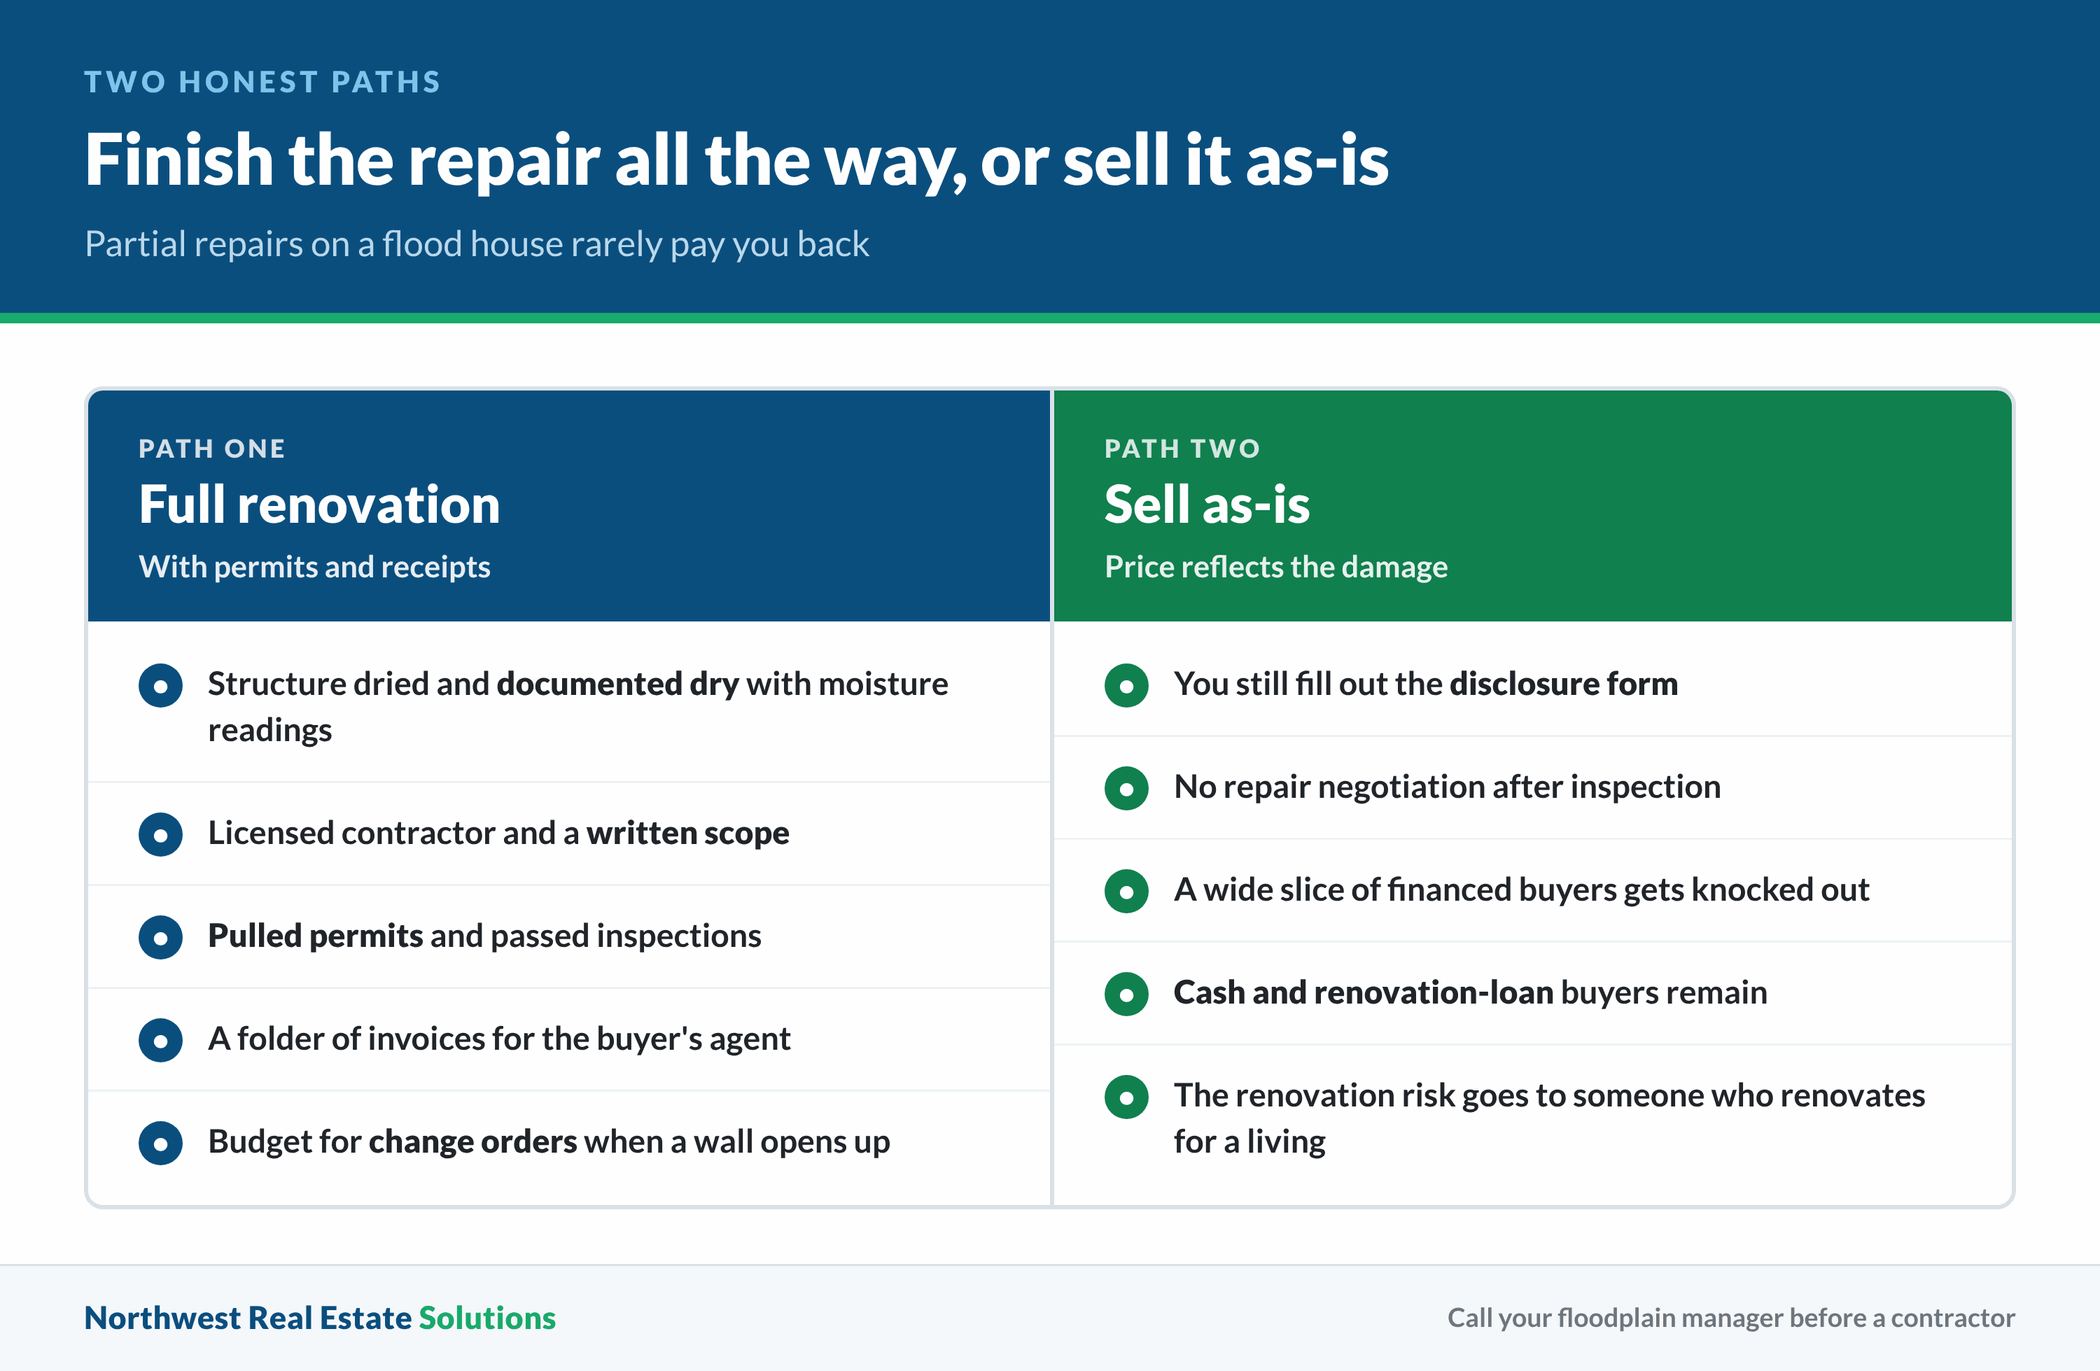
As-is governs condition, not candor. You still fill out the disclosure form and still answer the flood questions. What changes is that you’ve told the market up front: the price reflects the damage, and there’s no repair negotiation coming after inspection.
Common advice says fix it up and you’ll get your money back with interest. Partial repairs rarely work that way on a flooded house. New laminate over a subfloor that cupped tells a buyer’s inspector that somebody covered something, and the discount they demand is bigger than the discount you’d have taken by leaving it alone. Either take the renovation all the way through, with permits and receipts, or don’t start.
Taking it all the way through means something specific. It means the structure gets dried and documented dry with moisture readings before a single piece of new material goes in. It means a licensed contractor, a written scope, pulled permits, passed inspections, and a folder of invoices you can hand a buyer’s agent without apologizing. It means you’re prepared for the contractor to open a wall, find rot in a bottom plate, and come back with a change order. Budget for that conversation, because in a flood house it happens more often than it doesn’t. If reading that paragraph made your stomach drop, that’s useful information about which path you belong on.
Financing is the quiet gatekeeper. Appraisers flag standing water, missing flooring, and inoperable furnaces, and most conventional and government-backed loans want those items cured before funding. A wide slice of the buyer pool gets knocked out before anyone writes an offer. Cash buyers and renovation-loan buyers remain, which is a smaller, sharper group.
A few years back a widow in Springfield called me after two listings expired back to back. Neither one brought in a single written offer. Her split-level had taken water in the lower bedrooms, and the chest freezer in the garage still had the high-water line on it when I walked through on a Tuesday. Two agents, nine months, zero offers, and a mortgage payment every thirty days of it.

That’s not an indictment of agents. It’s what happens when a damaged property gets marketed to buyers who need financing on an undamaged property.
Consider what the surrounding market is doing while you decide. Eugene homes averaged $583,800 in September 2026, with a median of $520,000, going under contract in about 45 days on 2.3 months of supply, according to local MLS data compiled for Lane County. Those are solid numbers, and a clean house in that market moves fast. Your flooded one is competing in a different lane entirely, and the days-on-market figure for undamaged inventory tells you almost nothing about your timeline.
Mold remediation bids are where sellers get whiplash. Get three of them, from licensed contractors, and watch how far apart they land on the same house, something I’ve seen firsthand when sizing up deals myself. One will scope containment, negative air, and selective demolition; another will quote a fogging treatment and call it done. The spread between those two bids is often larger than the discount a cash buyer would ask for, taking the whole problem off your hands.
Make the bids comparable before you compare them. Ask each contractor the same three questions: what exactly gets removed, who does the clearance testing when you’re finished, and what happens to the price if you open a wall and find more than you expected. A bidder who won’t commit to clearance testing by someone other than himself is quoting a different job than the one you need. Keep the written scopes. Even if you never do the work, a serious remediation scope is a document a buyer can underwrite against, and it beats a verbal estimate every time.
Skip the permit step in a floodplain and you’re asking for trouble down the line. Jurisdictions along the Willamette and the Rogue enforce elevation and compliance rules on repairs that significantly alter a structure. Work done without a permit after a flood event can surface later as an open code issue. Call your city or county floodplain manager before you call a contractor. That one phone call has saved sellers. I’ve worked with them on financing repairs they were never allowed to make.
Selling as-is isn’t surrender. It’s recognizing that the person best equipped to absorb a renovation risk is the person who does renovations for a living.
Is a Cash Home Buyer Right for Your Oregon House? What Makes Us Different
Most cash offers written in Oregon get assigned to a third party before closing, and the seller usually learns this when an unfamiliar face shows up for the final walkthrough.
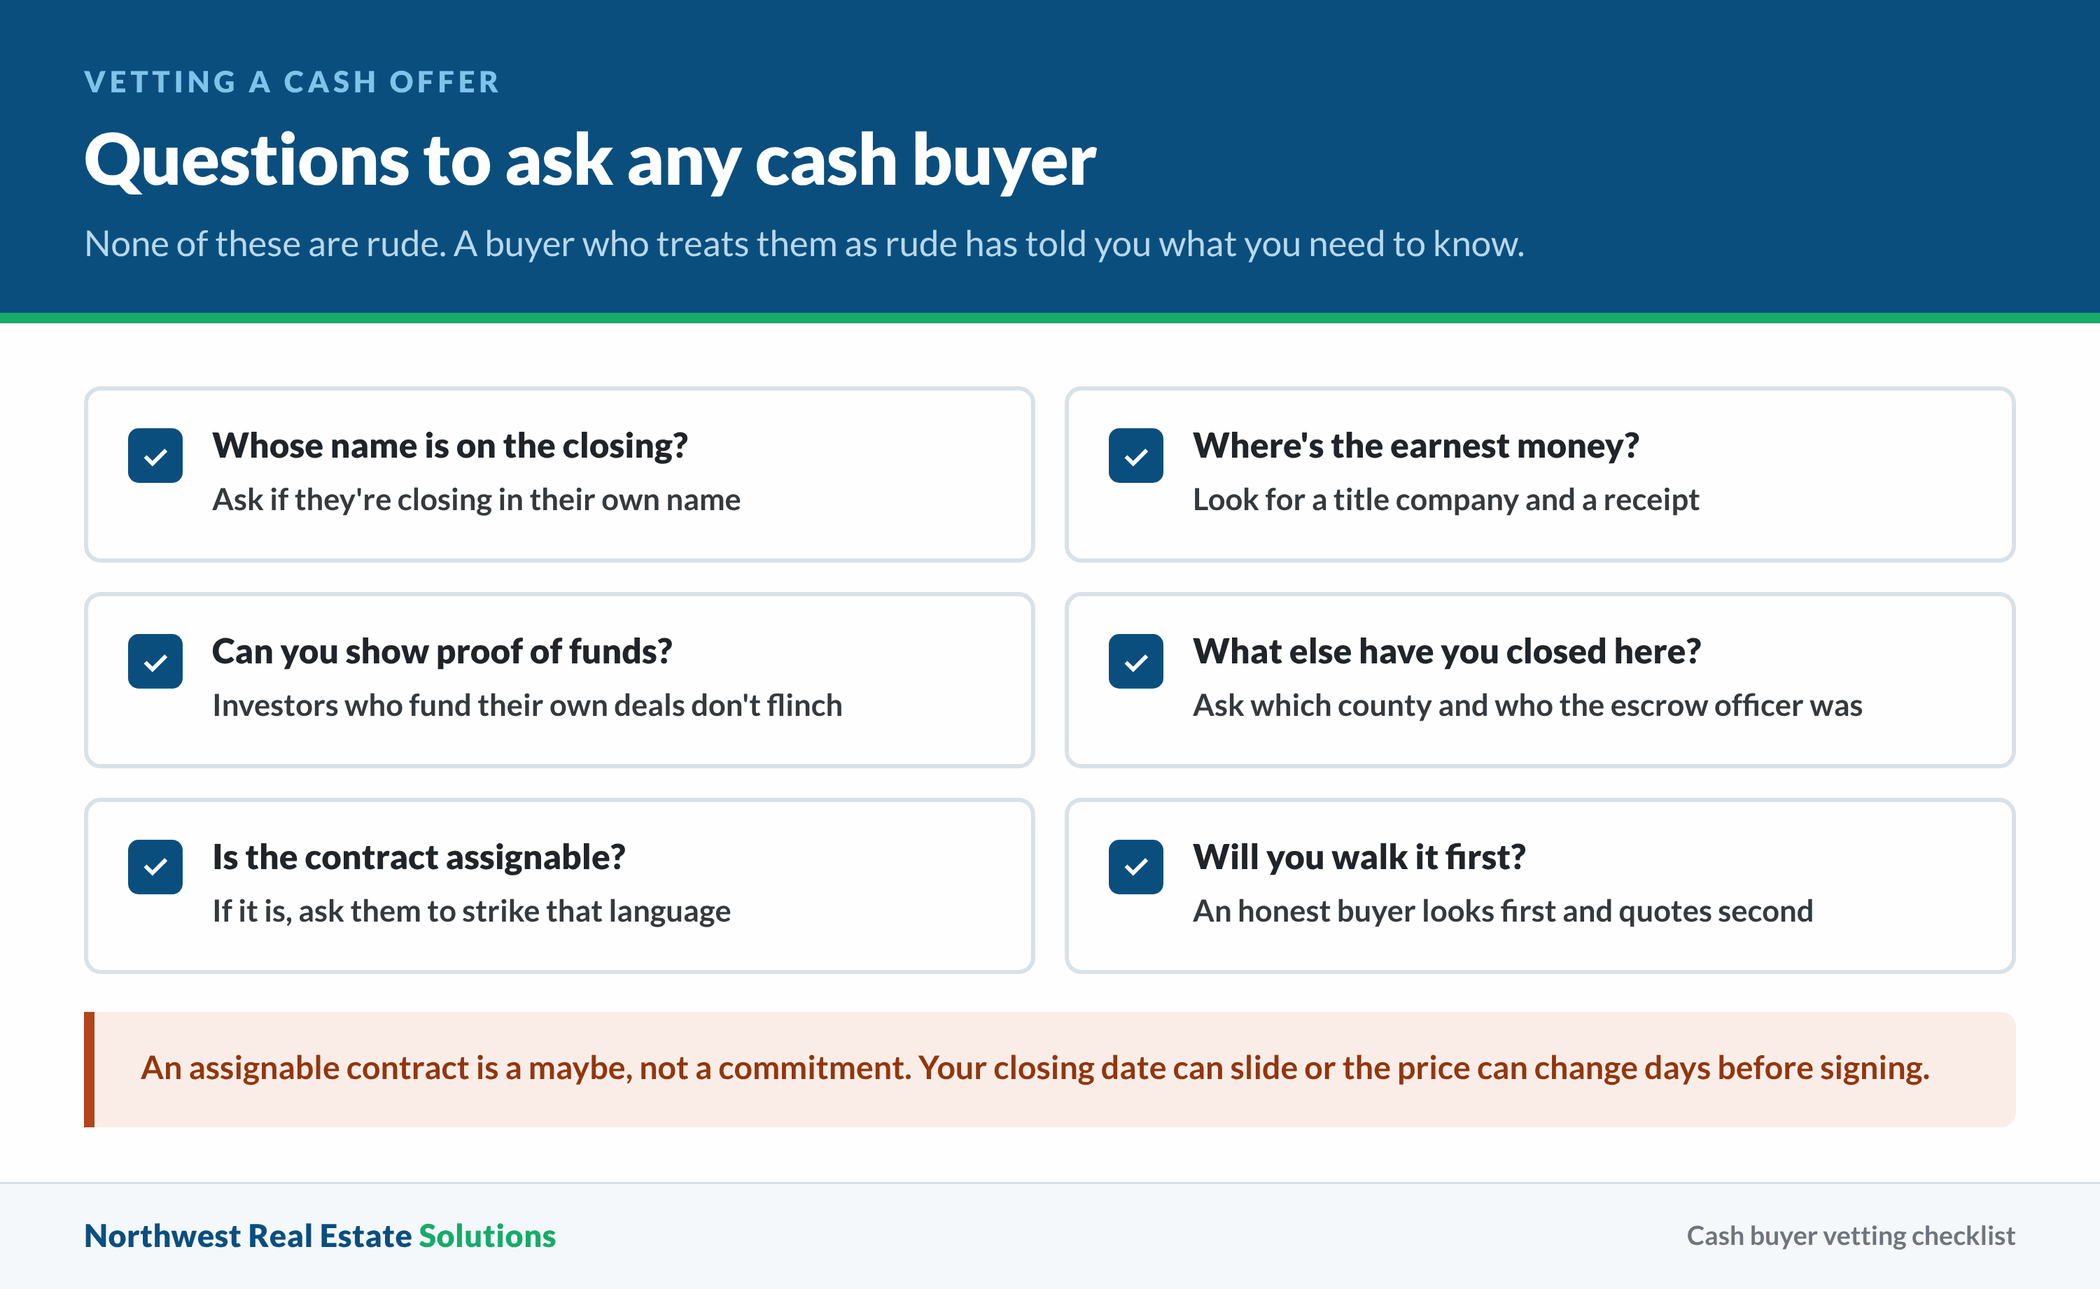
That’s legal. It’s also worth knowing, because an assignable contract is a maybe, not a commitment. The buyer who signed your agreement is shopping it. If no one bites at their markup, your closing date slides, or the price gets renegotiated three days before signing.
Ask any cash buyer two questions. Are you closing in your own name, and where is the earnest money sitting? A real answer involves a title company, a receipt, and a legal contract that doesn’t give the buyer unlimited rights to walk. Investors who fund their own deals don’t flinch at either question.
While you’re at it, ask these too. Can you show me proof of funds? What else have you closed in this county, and who was the escrow officer? Does this contract let you assign it, and if so, will you strike that language? None of those questions are rude. A buyer who treats them as rude has told you everything you needed to know, and it took four minutes.
At Northwest Real Estate Solutions, we buy with our own funds and close through a licensed Oregon title and escrow company, which means the offer you accept is the one that funds. We’ve bought houses with mushrooms growing out of the baseboard trim. Water damage doesn’t scare us off; it just shows up honestly in the price.

The process on our end is unglamorous on purpose. A phone call, a walkthrough where somebody actually gets into the crawlspace with a flashlight, a number, and a closing date you pick. No staging, no open houses, no cleanout, and you can leave the freezer or the couch that got wet. We’ve hauled worse.
You gain real value from speed in a damaged-property sale, and the math isn’t abstract. Total market time across the Portland metro ran 57 days in August 2026, up from 54 in July. Add escrow, add the appraisal, add a lender’s repair conditions, and a listing that goes perfectly still has you carrying taxes, utilities, and insurance into a fourth or fifth month. A direct sale compresses that to a couple of weeks.
What does a buyer give up with a cash offer? Price, usually. An investor underwrites to the after-repair value minus the renovation budget minus a margin, and that number lands below what a restored house would fetch on the open market. Anyone who tells you otherwise is selling something.
It buys you certainty: no appraisal, no inspection renegotiation, no financing contingency, and no buyer walking because their insurer declined to quote a property with a flood claim on file.
There are sellers who shouldn’t take a cash offer. If your damage was cosmetic, your insurance claim paid out, and the repairs are already finished with permits in hand, list it. You’ll do better. The cash route earns its keep when the damage is open, the money to fix it isn’t there, or the timeline is driven by something other than price.
Property valuations on flood houses are genuinely hard, which is why I’d push back on anyone who hands you a number over the phone without walking the property, a lesson I learned after guessing wrong myself more than once. Two houses on the same Oregon street can differ by forty grand in repair scope depending on whether the water hit the ductwork. An honest buyer looks first and quotes second and offers no guarantees before seeing the crawlspace.
What Happens at Closing on a Flood-Damaged Oregon House
Escrow is where flood sales die, and it’s almost never the water that kills them.
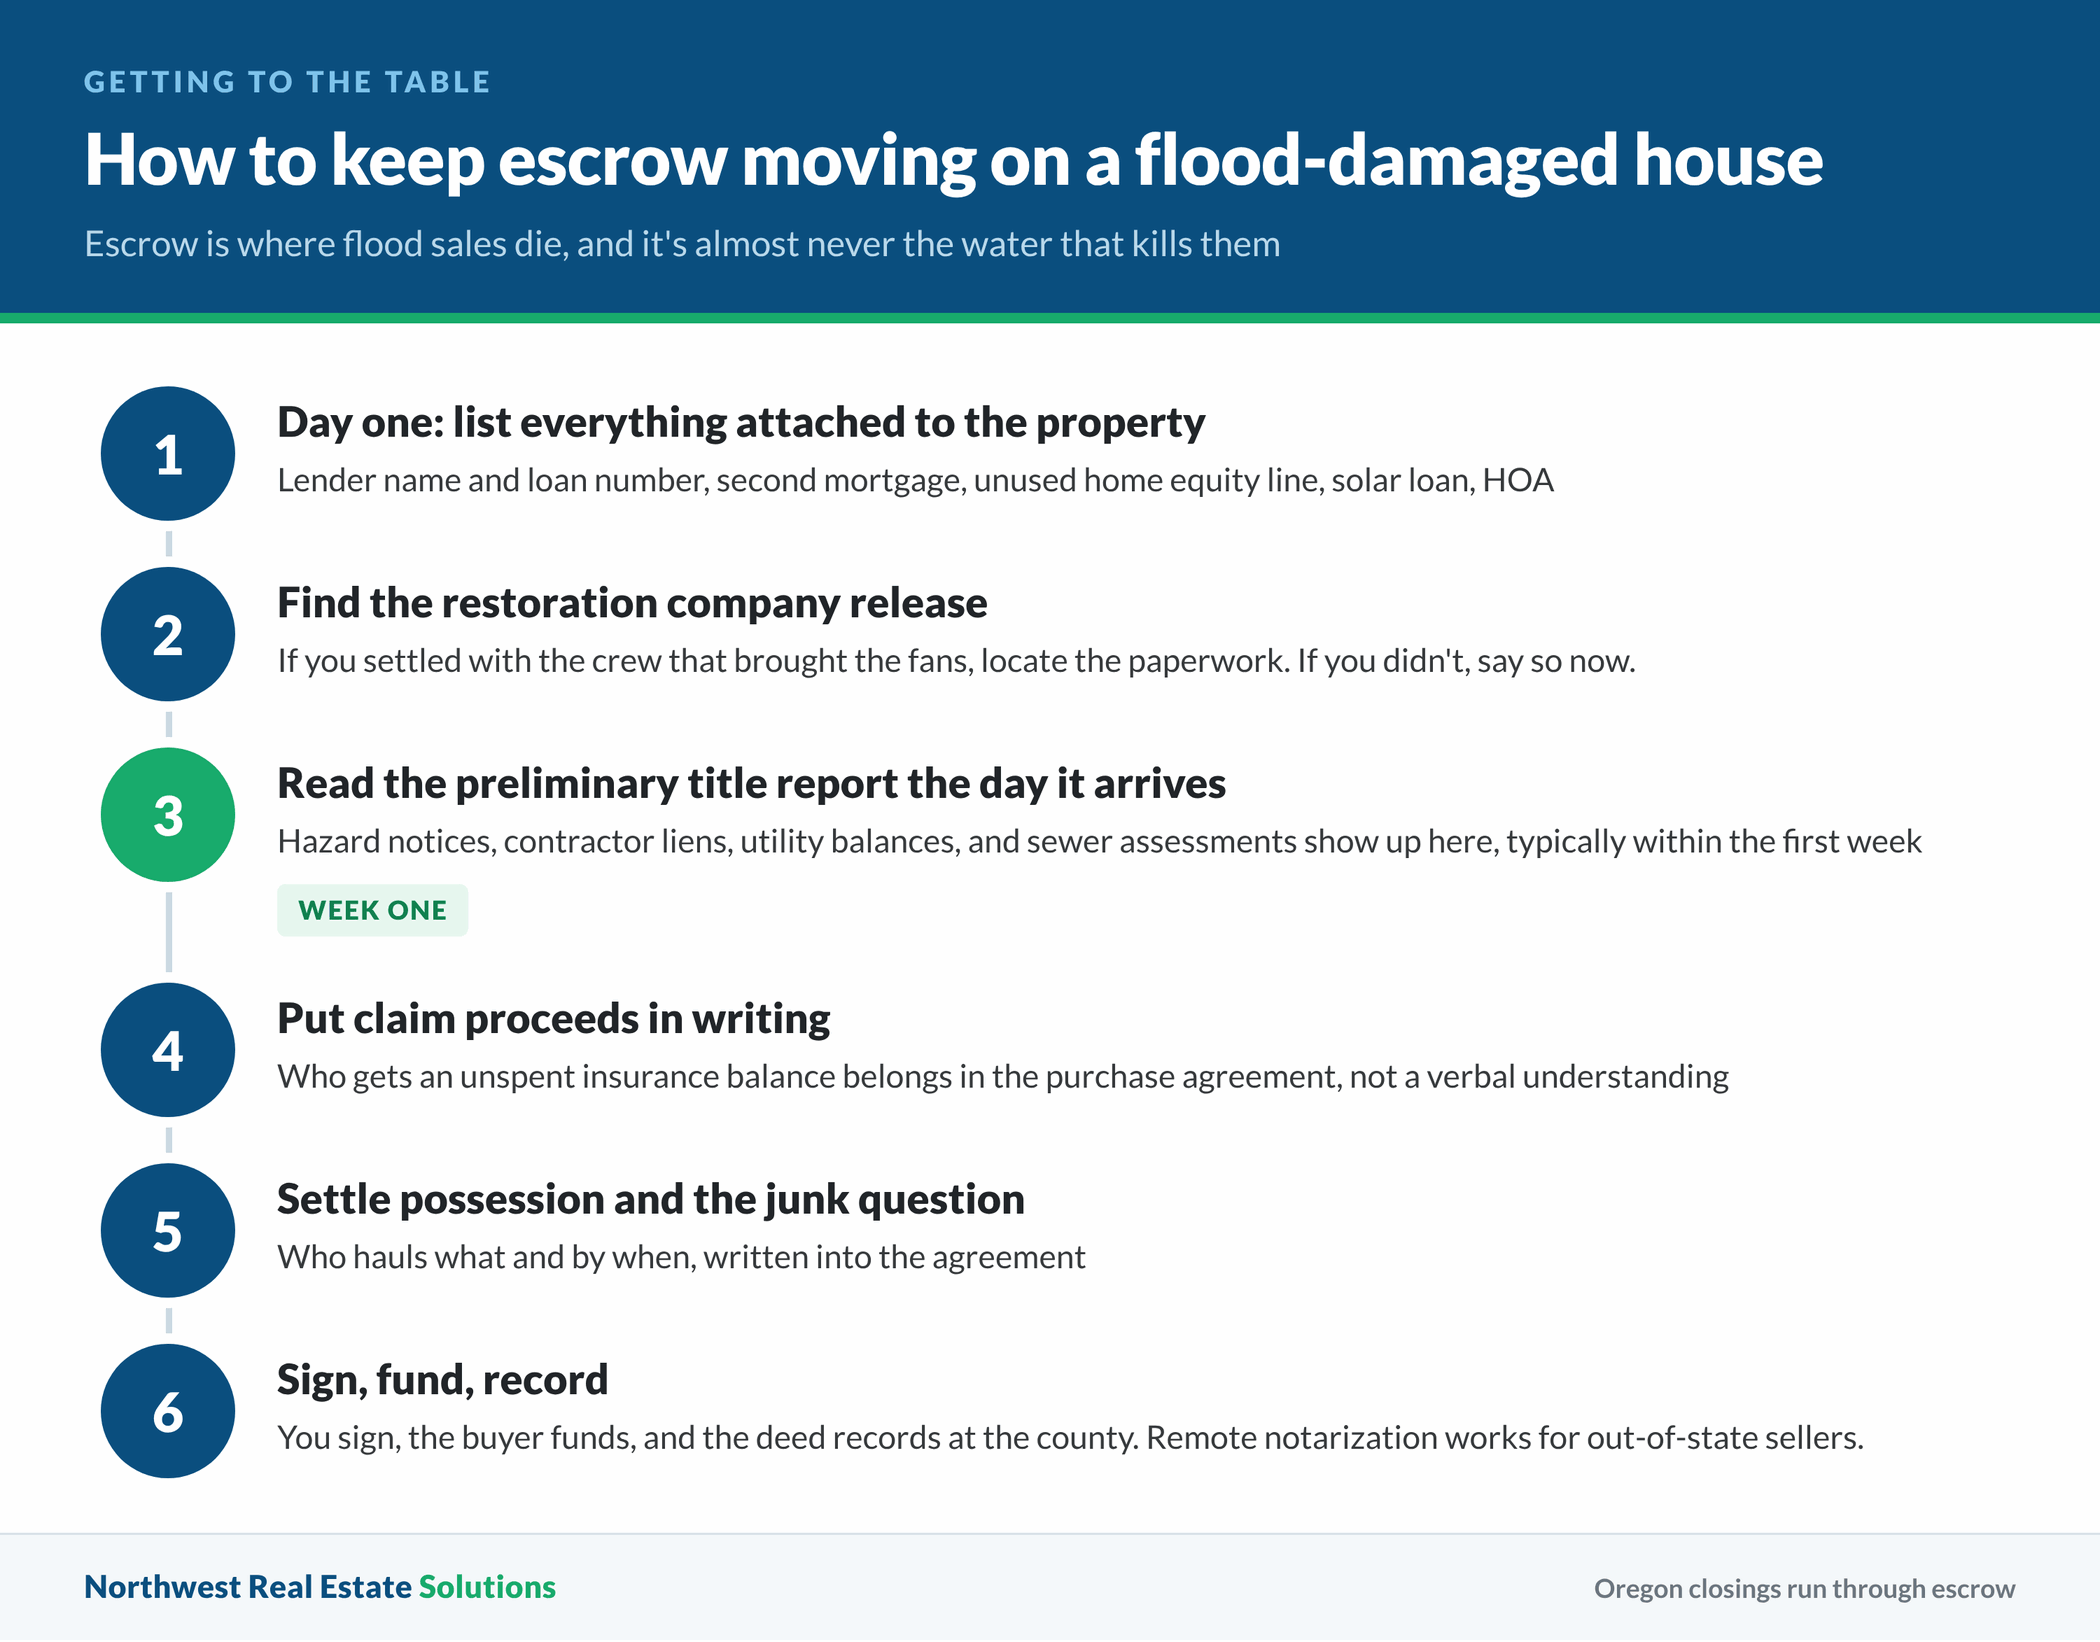
The title is the usual culprit. A recorded hazard notice, an old contractor’s lien from a restoration crew that never got paid in full, a utility balance, or a sewer assessment—any of these can stall funding until it’s resolved. Your escrow officer will surface them in the preliminary title report, typically within the first week. Read that report the day it arrives rather than the day before signing.
Most of this stuff is avoidable if you move early. Hand your escrow officer the lender’s name and loan number on day one, plus anything else attached to the property: a second mortgage, a home equity line you stopped using years ago, a solar loan, or an HOA. The emergency restoration company that showed up with fans the week of the flood belongs on that list too. If you settled with them, find the release. If you argued with them and never finished the conversation, say so now rather than letting a title examiner find it for you.
Open insurance claims complicate the file in a specific way. When your insurer has issued payment on a structural claim and the repairs weren’t completed, the mortgage servicer often holds those funds in a restricted account and releases them against completed work. Who ends up with that balance at closing is a negotiation between you, the buyer, and the lender, and it belongs in the purchase agreement in writing. I’ve watched verbal understandings about claim proceeds fall apart in escrow with impressive consistency.
Insurance adjusters can help you here, oddly enough. A final adjuster’s report with a line-item scope gives the buyer a documented damage estimate, which tends to steady a nervous negotiation better than any seller’s reassurance.

The escrow officer handles prorations: property taxes, any prepaid insurance, and utilities. Your county assessor’s office can confirm the current assessed figures if the numbers in escrow look off to you. Don’t guess at them and don’t let a buyer tell you what they should be.
Oregon closings run through escrow, so you sign, the buyer funds, and the deed records at the county. You generally don’t sit across a table from your buyer. For out-of-state sellers, including heirs handling a parent’s house from California or Arizona, remote notarization and overnight documents make the whole thing manageable without a plane ticket.
Possession is worth settling early. If you need a week after recording to finish clearing the garage, say so during negotiation and get it written into the agreement. A buyer planning to gut the place rarely objects. A buyer planning to move in on Saturday absolutely will.
Settle the junk question in the same breath. Who hauls what, and by when? On a floodhouse there’s usually more to deal with than anyone estimates, and in my own deals it’s always more than the seller guesses: warped furniture, boxes in the lower level nobody wants to open, and a water heater lying on its side. Decide in the contract whether personal property left behind is a problem or a non-issue, because discovering the answer on recording day is how friendly transactions turn sour.
Central Oregon illustrates why closing certainty beats list price on a damaged house. Bend’s median days on market stretched from 27 in July to 34 in August 2026 as closed sales dropped. Markets shift under you as you wait, and a contract that’s already funded doesn’t care what next month’s inventory does.
One pattern I keep seeing: sellers who negotiate hard on price and then accept vague contract language on everything else. Closing date, possession, who hauls the junk, and what happens if the title work turns up a surprise. You end up fighting over one line in a document with thirty of them, and the other twenty-nine determine whether you get to the table at all.
What’s Next After You Sell Your Flooded Oregon Home
Redmond’s median sale price came in at $480,000 in August 2026, down from $525,000 in July, with homes going pending in a median of 19 days. That kind of swing is why sellers leaving a damaged house in one Oregon town should look hard at the next one before committing.
Your first stop after closing isn’t a house hunt, though. It’s your lender payoff statement and your tax picture. Proceeds pay the mortgage, any liens, escrow fees, and whatever the agreement assigned to you, and what lands in your account afterward may or may not be taxable. A long-standing federal exclusion shields a chunk of gain on a primary residence for owners who meet the ownership and use requirements, and casualty losses from federally declared disasters follow their own rules. A CPA who has handled disaster-area returns earns their fee in one meeting.
Keep every document. Claim correspondence, adjuster reports, remediation invoices, permits, and the signed disclosure. Store them digitally and keep them for years. Questions about a property’s flood history have a way of resurfacing long after everyone’s moved on.
When you do start looking at the next house, ask the seller every question you just spent months answering. Pull the disclosure form apart line by line. Walk the lot after a hard rain if you can manage it, look at where the downspouts discharge, and get a flood insurance quote before you’re under contract rather than during underwriting. People who have been flooded once tend to make excellent buyers because they know exactly which crawlspace hatch to open.
Renting for a year isn’t a failure, either. Oregon’s rental market gives you a place to breathe as you figure out whether you want to be near water again. Plenty of sellers I’ve worked with used that year to decide they’d rather be in Hillsboro or Albany than back on the same creek.
An heir in Gresham called me on a Thursday, three months behind on a mortgage he’d inherited along with the house, with an auction date already on the calendar and a motorcycle still parked under the carport. The lower level had flooded the winter before his father passed, and nobody had touched it since. We closed before the sale date, and he kept the bike.
Situations like that one are the reason I’d rather someone call too early than too late. A seller with sixty days has choices. A seller with six has one.
If you’re weighing a listing against a direct sale, get both numbers in front of you. A local agent can give you a realistic price for the repaired property and an honest repair estimate. Northwest Real Estate Solutions can give you a cash number on it as it stands today, with no repairs and no cleanout required. Put the two numbers side by side, net of carrying costs and commissions, and you’ll have the only honest way to make this decision.
Frequently Asked Questions
How Do You Sell a House That Needs to Be Torn Down?
You sell the land and the location, not the structure, and you price it that way from the first conversation. Buyers for a teardown are builders and investors who care about lot size, zoning, utility hookups, and whether a floodplain designation limits what can be rebuilt there. Financing almost never works on these, so expect cash offers, and check with your city’s planning department about rebuild restrictions before you market the property.
Is It Against the Law to Sell a Car That’s Been Flooded?
Selling a flood-damaged vehicle isn’t automatically illegal, but hiding the damage is. Title branding rules exist in Oregon for exactly this reason, and the DMV is the right office to ask about how a salvage or flood brand applies to your specific vehicle. Real estate and vehicles follow completely separate disclosure systems, so nothing in your home sale carries over to the car in the driveway.
Is Oregon a Buyer’s Market or a Seller’s Market Right Now?
Depends on where you stand and what you’re selling. Portland showed about 4.1 months of inventory in September 2026, which reads as balanced rather than tilted, with just under a third of properties closing above original asking price. Damaged houses live in their own submarket, though, and in that one the buyer always has leverage because the pool of people willing to take on water damage is small.
What Should You Avoid Saying When You’re Selling a House?
Skip speculation and skip anything you can’t support. Telling a buyer the crawlspace “probably dried out fine” when you never had it inspected creates a problem you don’t need, and so does downplaying a repair you didn’t permit. State what you know, attach documentation to the disclosure form where it’s requested, and let the buyer’s own inspection fill in the rest.
If you’re sitting on a flooded house in Oregon and you’re not sure what it’s worth or what your options look like, we’re happy to talk it through. Ask questions, get a number, compare it to what an agent tells you, and take whichever path makes sense for your situation. No pressure, no obligation, and no hard feelings if you decide to list it instead.
We Buy Flood-Damaged Houses in Portland and Across Oregon
Portland is our main market, and it keeps moving even when a house carries a flood file. RMLS counted 1,902 closed sales across the Portland metro in August 2026. Most of those homes sold clean to buyers with lenders. A flooded house sells on a different track, and that’s the track we work on.
We’re cash home buyers in Portland, and we look at water-damaged homes all over the state. Farther south, we buy houses in Salem and work as investor home buyers in Eugene. East of the city, we’re also a company that buys homes in Gresham. You can see the full list of places we buy houses in Oregon, or meet the Northwest Real Estate Solutions team before you call.
Talk Through Your Flood-Damaged House With Us
You don’t need to dry out the crawlspace or haul off the wet furniture before you ask us for a number. Tell us when the water came in, what the insurer paid, and what paperwork you’ve kept. We’ll walk the house, look under it, and give you a cash offer you can set next to a listing price.
Still have questions first? Check out other frequent questions. When you’re ready, fill out our quick contact us form or use the short form below, and we’ll take it from there.
Helpful Oregon Blog Articles
- Who Is Responsible For HOA Fees At Closing In Oregon
- Guide To Oregon Inheritance Laws
- Paperwork For Selling Your Oregon Home by Owner
- Understanding Squatters’ Rights In Oregon Real Estate
- How To File A Quitclaim Deed For Real Estate In Oregon
- Homeowners Insurance When Selling a House in Oregon
- Can You Sell a House with Asbestos in Oregon
- How to Sell a House with Mold in Oregon
- Can the Seller Back Out of a Contract in Oregon?
- How Much Equity Do I Need to Sell My House in Oregon?
- Taxes When Selling an Inherited House in Oregon
- Do Open Houses Still Work When Selling a Home in Oregon?
- How to Sell a House with Flood Damage in Oregon