Oregon is one of the only states in the country where a city or county is flatly barred from taxing you just for handing over the deed to your house. One county got grandfathered in decades ago. Everybody else closes transfer-tax free, which saves Oregon sellers money that folks in Washington and California never see. People are fooled by that quirk into thinking closing here is cheap. It isn’t. The money just moves to other line items: commission, title, escrow, prorated property taxes, and a lender checklist that keeps growing right up until signing day.
How Much Are Closing Costs in Oregon?
$506,889. That was the median sale price for an Oregon home in August 2026, according to Redfin’s state market data, down a slim 0.6 percent from the year before. Apply closing costs to a number like that and you stop thinking of them as an abstraction fast.
In this market, buyers typically set aside 2 to 5 percent of the purchase price for their share of the costs, while sellers end up carrying more of the weight. Once agent commission is folded in, the seller side of an Oregon sale commonly lands between 6 and 10 percent of the sale price.
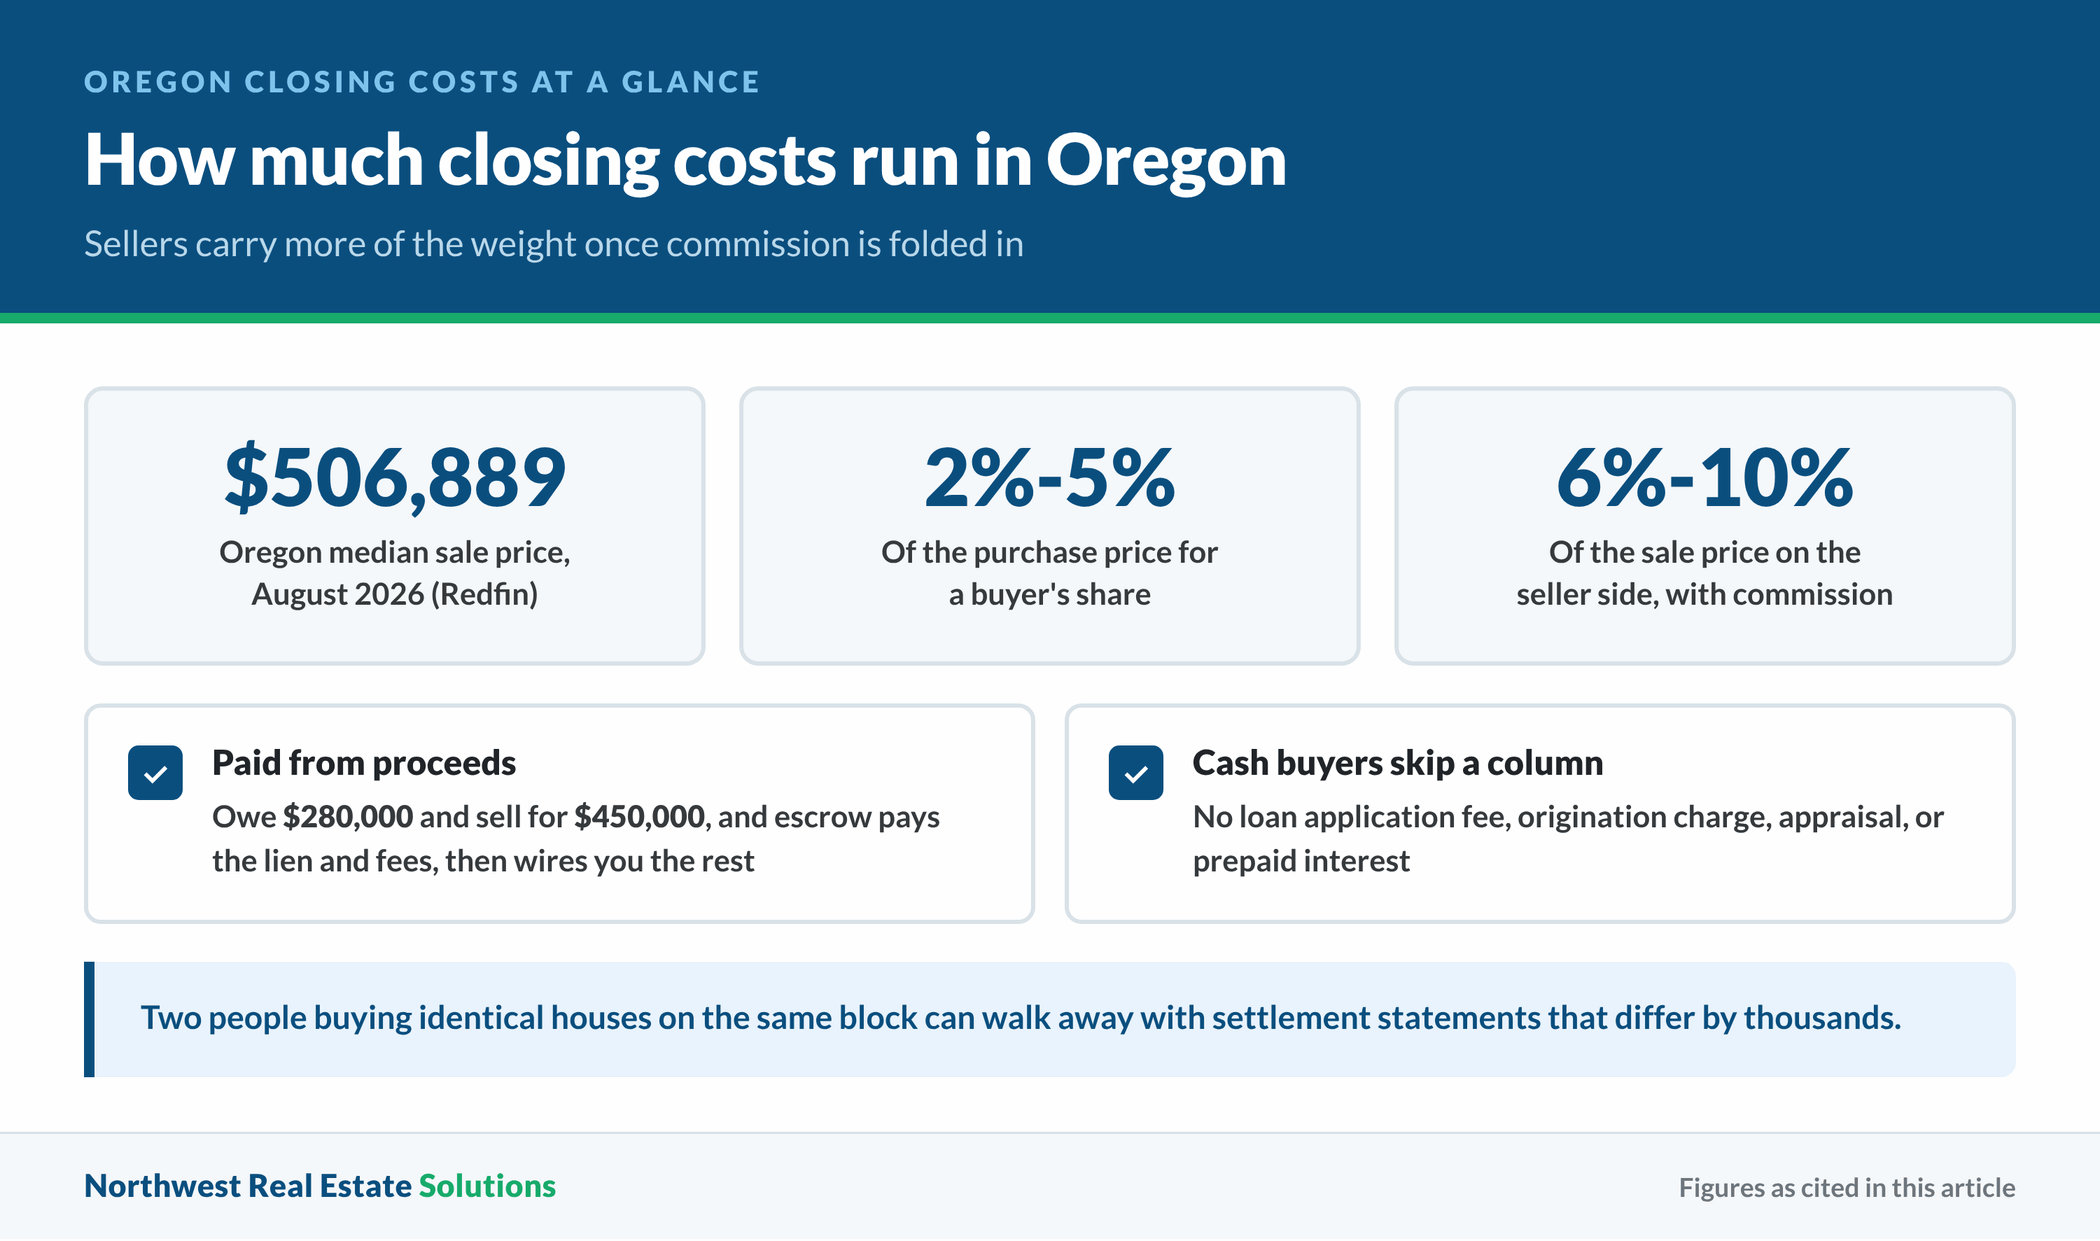
A cash buyer skips the lender column entirely: no loan application fee, no origination charge, no appraisal, and no prepaid interest. Someone financing with a low down payment picks up all of it plus mortgage insurance. Two people buying identical houses on the same block in Beaverton can walk away with settlement statements that differ by thousands.
Budgeting carefully for commission, sellers then forget the rest, which is something I run into again and again with clients. The proration of property taxes alone can shift a few thousand dollars depending on what month you close, and nobody warns you about that at the listing appointment.
One more thing worth building into your plan: closing costs come out of proceeds, not out of your checking account. If you owe $280,000 on your mortgage loan and sell for $450,000, the escrow agent pays off the lien, pays the fees, and wires you what’s left. You’re not writing a check at the table unless your payoff and costs exceed the price.
Anyone buying and selling in the same week should mind ordering. Your proceeds don’t land in your account the second you sign. The escrow officer records the deed with the county, confirms recording, then disburses, and depending on the hour you sign and the county’s recording cutoff, that can push funding to the following business day. Counting on sale proceeds to fund the down payment on your next house means telling both escrow officers early so they can sequence the closings instead of leaving you stranded between them for a day.
Are Oregon Closing Costs Above Average?
When Maria sold her late father’s house last spring, she braced for the high fees common just across the border. She didn’t need to, and that’s not luck; it’s law. Oregon closes are cheaper than the states on either side of us.
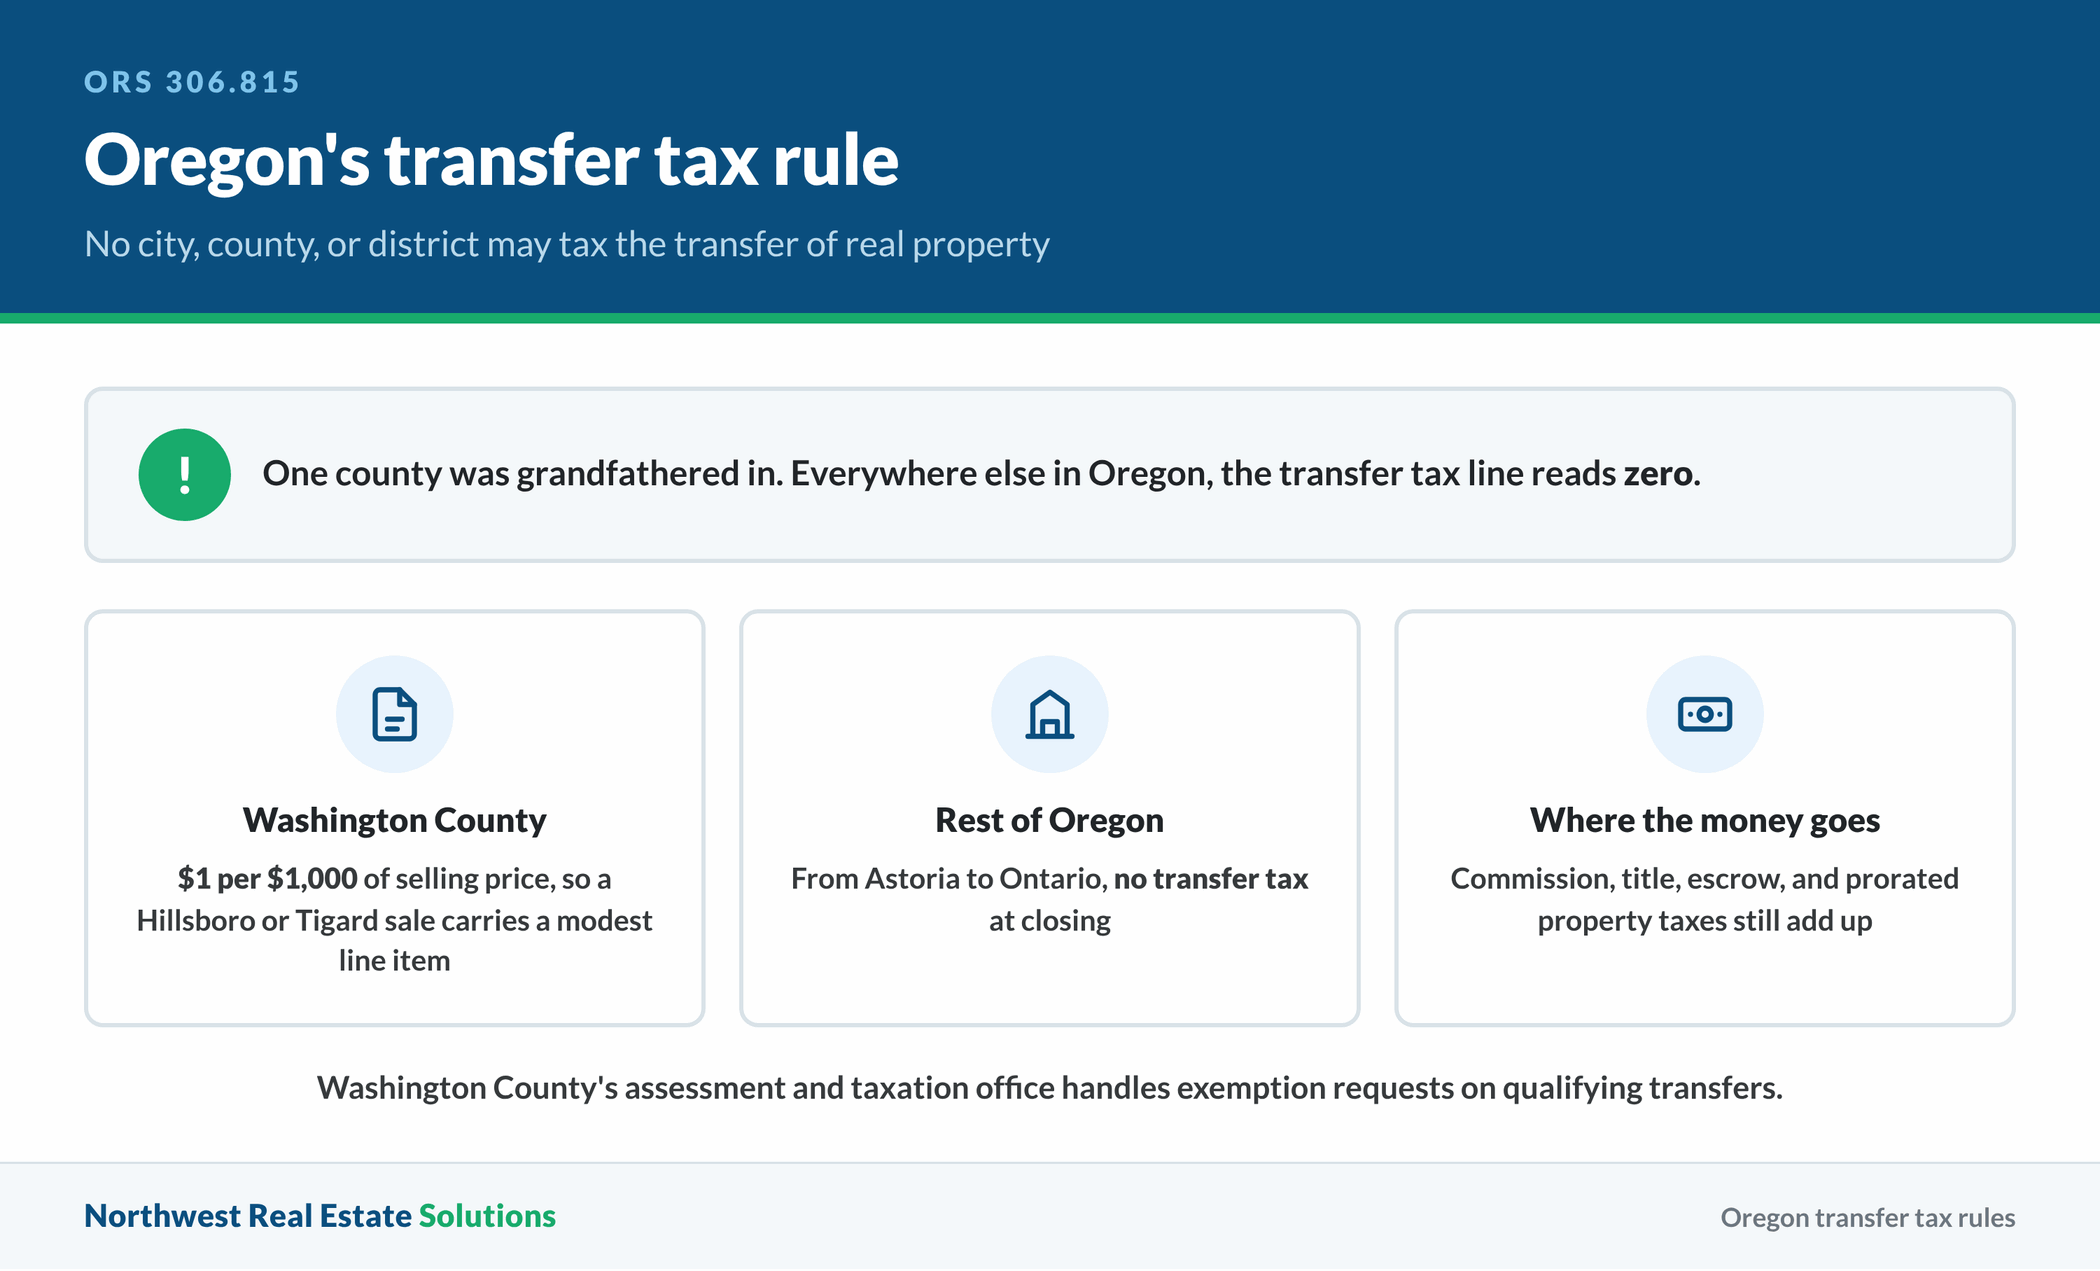
Under ORS 306.815, no city, county, or district in Oregon may impose a tax on the transfer of real property. Washington County is the lone survivor, with a tax of one dollar per thousand dollars of selling price under its county code. On a Hillsboro or Tigard sale, that’s a modest line item, and the county’s assessment and taxation office handles exemption requests on qualifying transfers. Everywhere else in the state, from Astoria to Ontario, that column reads zero.
Where Oregon lands overall comes down to taxes working in your favor, with everything else landing somewhere in the middle. Title insurance rates here run higher than in some Midwest states. Escrow and settlement charges track the national middle. What really decides whether your closing feels expensive is commission, and that’s the one line nearly everybody treats as fixed even though it never has been. A good place to start is checking how much it costs to list your Oregon home on the MLS.
Someone telling you Oregon has high closing costs should be asked which line item they mean. Usually they’re describing the commission, not the state.
What Do Oregon’s Closing Costs Include?
“Escrow fee, settlement fee, title fee. Isn’t that the same charge billed three times?” Fair objection, and no. The title company researches ownership history and issues the insurance policy. Escrow is the neutral third party holding funds, recording documents, and disbursing money. Most Oregon transactions close through title companies rather than attorneys, so both services often appear on one invoice from one roof, which is exactly why it looks like duplication.
On the lender side, the list gets longer. Loan application and processing fees, a credit report pull, an appraisal typically in the $400 to $700 range, and an origination charge that usually runs half a percent to a full percent of the loan amount. Discount points are optional: each one costs about 1 percent of the mortgage and buys down your rate. Mortgage points make sense if you’re staying put a decade. They rarely pencil out if you’ll refinance or move in three years.
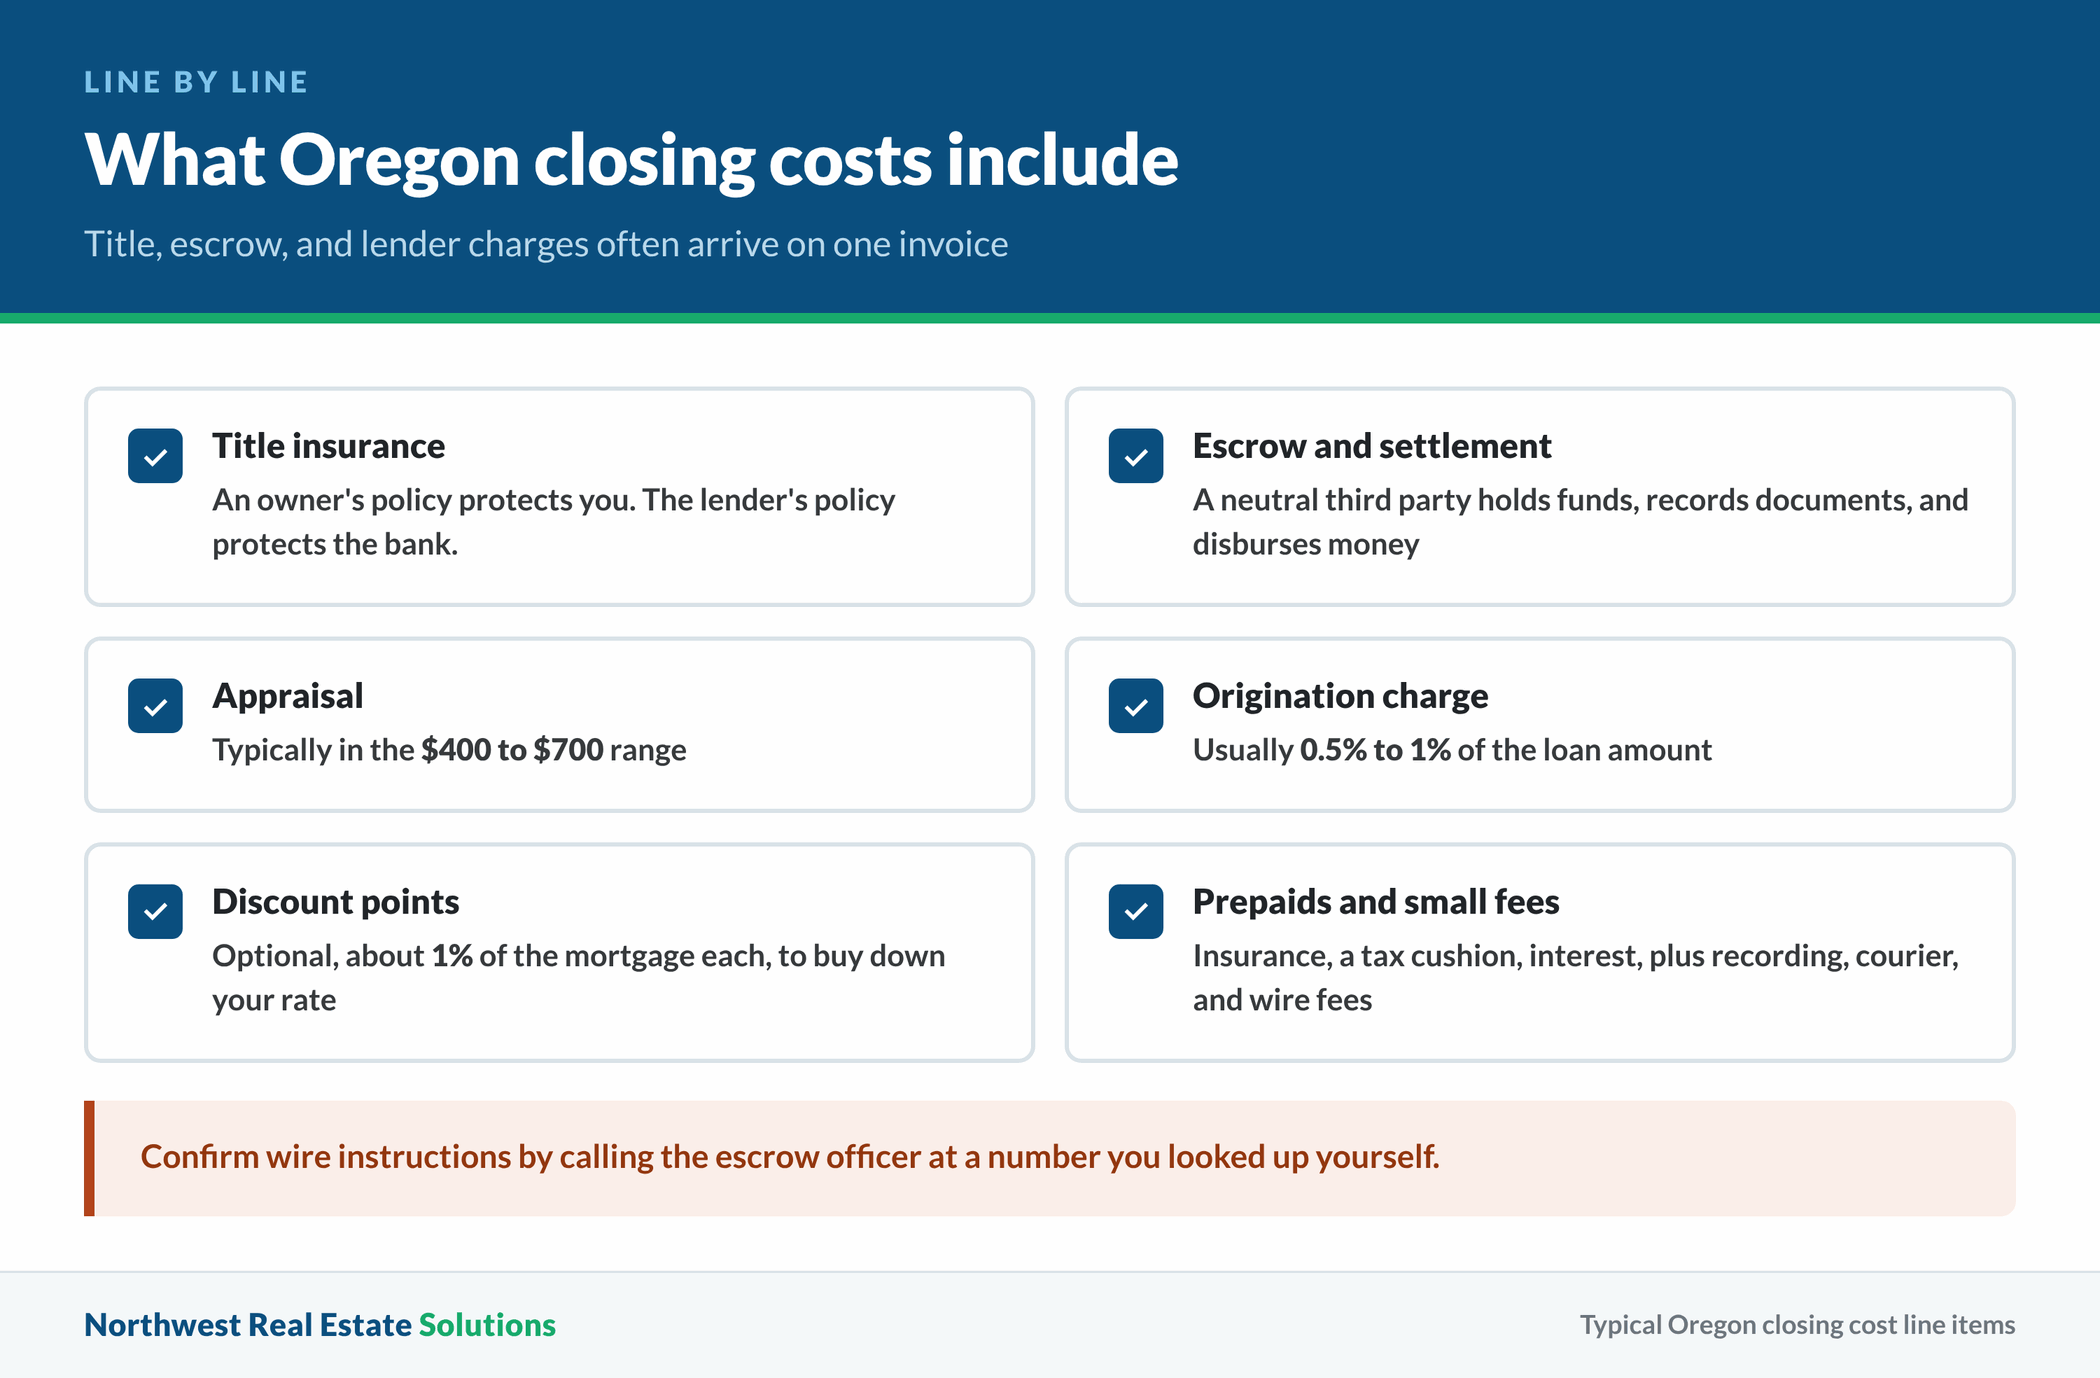
Title insurance in Oregon is often quoted around $7.67 per thousand dollars of coverage. Two policies exist. The owner’s policy protects you; the lender’s title insurance protects the bank. Both get issued at closing, and only one of them is for your benefit.
Then come the prepaids, which aren’t fees at all. Your first homeowners insurance premium, a cushion of property taxes, and interest covering the days between closing and your first payment all get collected up front. That total makes buyers assume they’re being gouged. You’re just prefunding your own escrow account.
Watch the small stuff too: recording fees, courier charges, wire fees, and sometimes a charge for the flurry of emails and document handling that follows a rush close. None of it is large alone. Stacked, it’s real money.
Signing day itself is shorter than people expect and mostly mechanical, and in every closing I’ve sat through as a buyer the actual signing takes less time than the small talk beforehand. You bring a photo ID, you sign a stack with a notary at the title company’s office or with a mobile notary at your kitchen table, and the money moves separately. Buyers should plan on wiring funds rather than carrying a personal check, and they should confirm wire instructions by calling the escrow officer at a number they looked up themselves. Wire fraud in real estate works by spoofing a familiar email thread at exactly the moment you’re expecting instructions. No legitimate escrow officer will be offended by a verification call, and that one phone call is the cheapest protection in the entire transaction.
What Affects Closing Costs in Oregon?
“Why does my neighbor’s closing statement look nothing like mine?”
Price does most of the work. Percentage-based charges scale directly, so the gap between selling in Portland, where the typical home value sat at $524,318 as of September 2026, and selling in Springfield, where the median sale price was $478,500 in September 2026, shows up on every commission and title line.
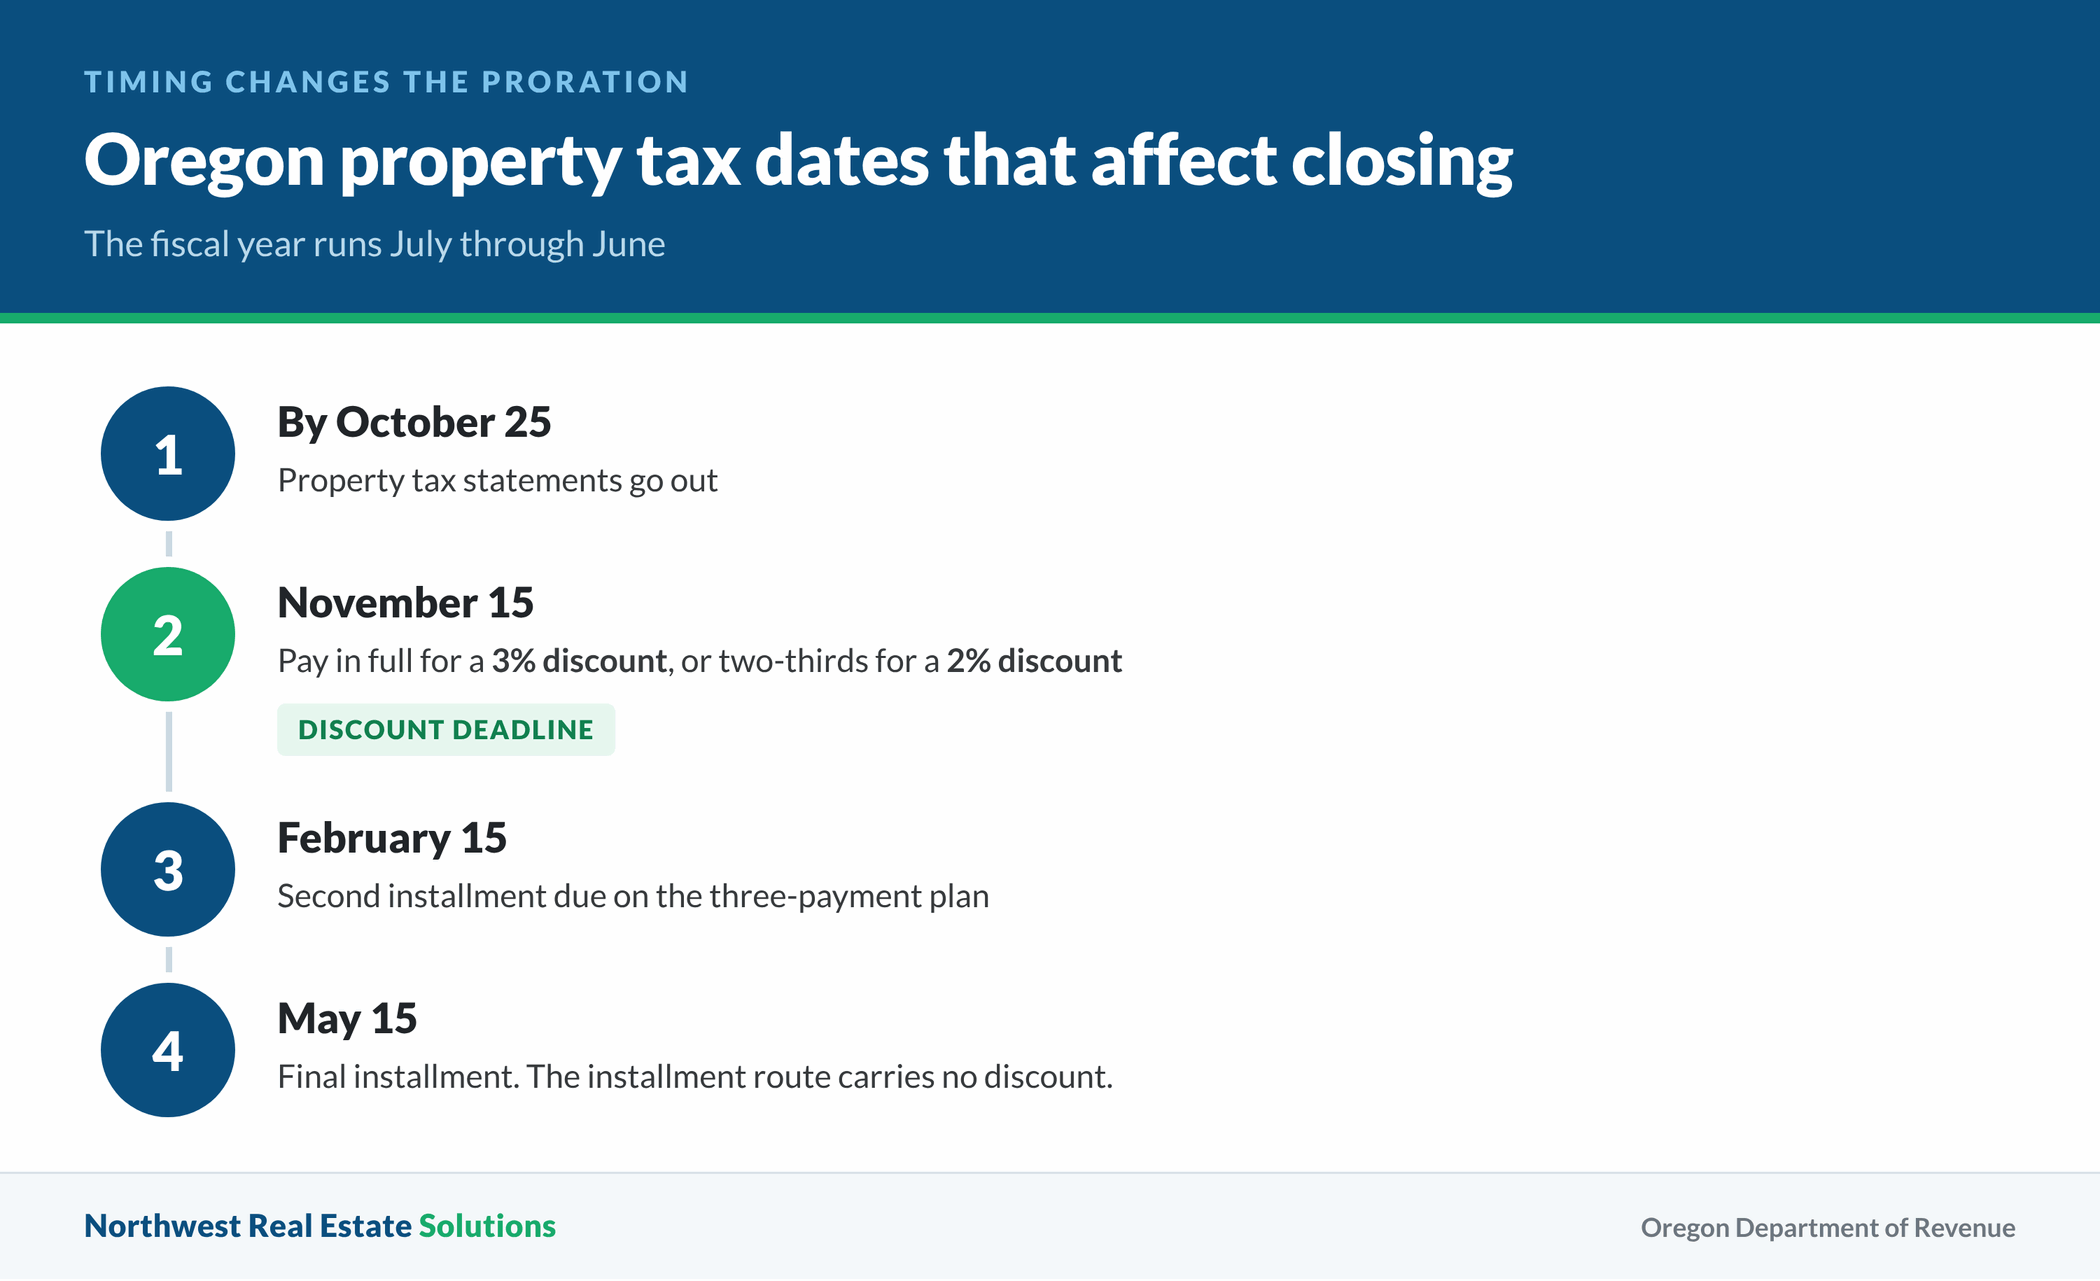
People rarely plan for how much timing matters. Oregon property taxes run on a July-through-June fiscal year, and statements go out by October 25 each year. Per the Oregon Department of Revenue, paying the full bill by November 15 earns a 3 percent discount, paying two-thirds by that same date earns 2 percent, and the three-installment route (November 15, February 15, May 15) carries no discount at all. If the 15th lands on a weekend or holiday, it rolls to the next business day. Close in September and you’ll credit the buyer for months of unpaid tax. Close in December, and the proration swings the other direction. Prorations are only one piece of the tax picture, and we’ve laid out the rest of your tax responsibilities when selling a home in Portland, OR.
Your loan type changes the picture too. FHA and VA files carry their own funding charges and stricter appraisal standards. Conventional financing with 20 percent down is the cheapest to close.
Property type adds its own line items. A condo or any home in an association brings document fees, a transfer or setup fee, and sometimes a demand for unpaid dues. All of these land on the settlement statement, whether anyone discussed them or not. Out in the rural counties, well and septic work shows up instead: a flow test, a water quality sample, a septic evaluation. Sellers who have a second mortgage, a HELOC they stopped thinking about years ago, or a contractor’s lien from a remodel will also pay to have each of those tracked down, paid off, and released, and every one of those payoffs has its own processing charge attached.
Repairs can show up out of nowhere and drive costs nobody priced in advance. Inspections turn up a failing roof or a cracked heat exchanger, the buyer asks for a credit, and suddenly your seller costs jumped four thousand dollars after the contract was already signed. Oregon homes spent a median of 39 days on market in August 2026, which means there’s plenty of runway for a repair negotiation to eat your margin.
Who Pays Closing Costs in Oregon?
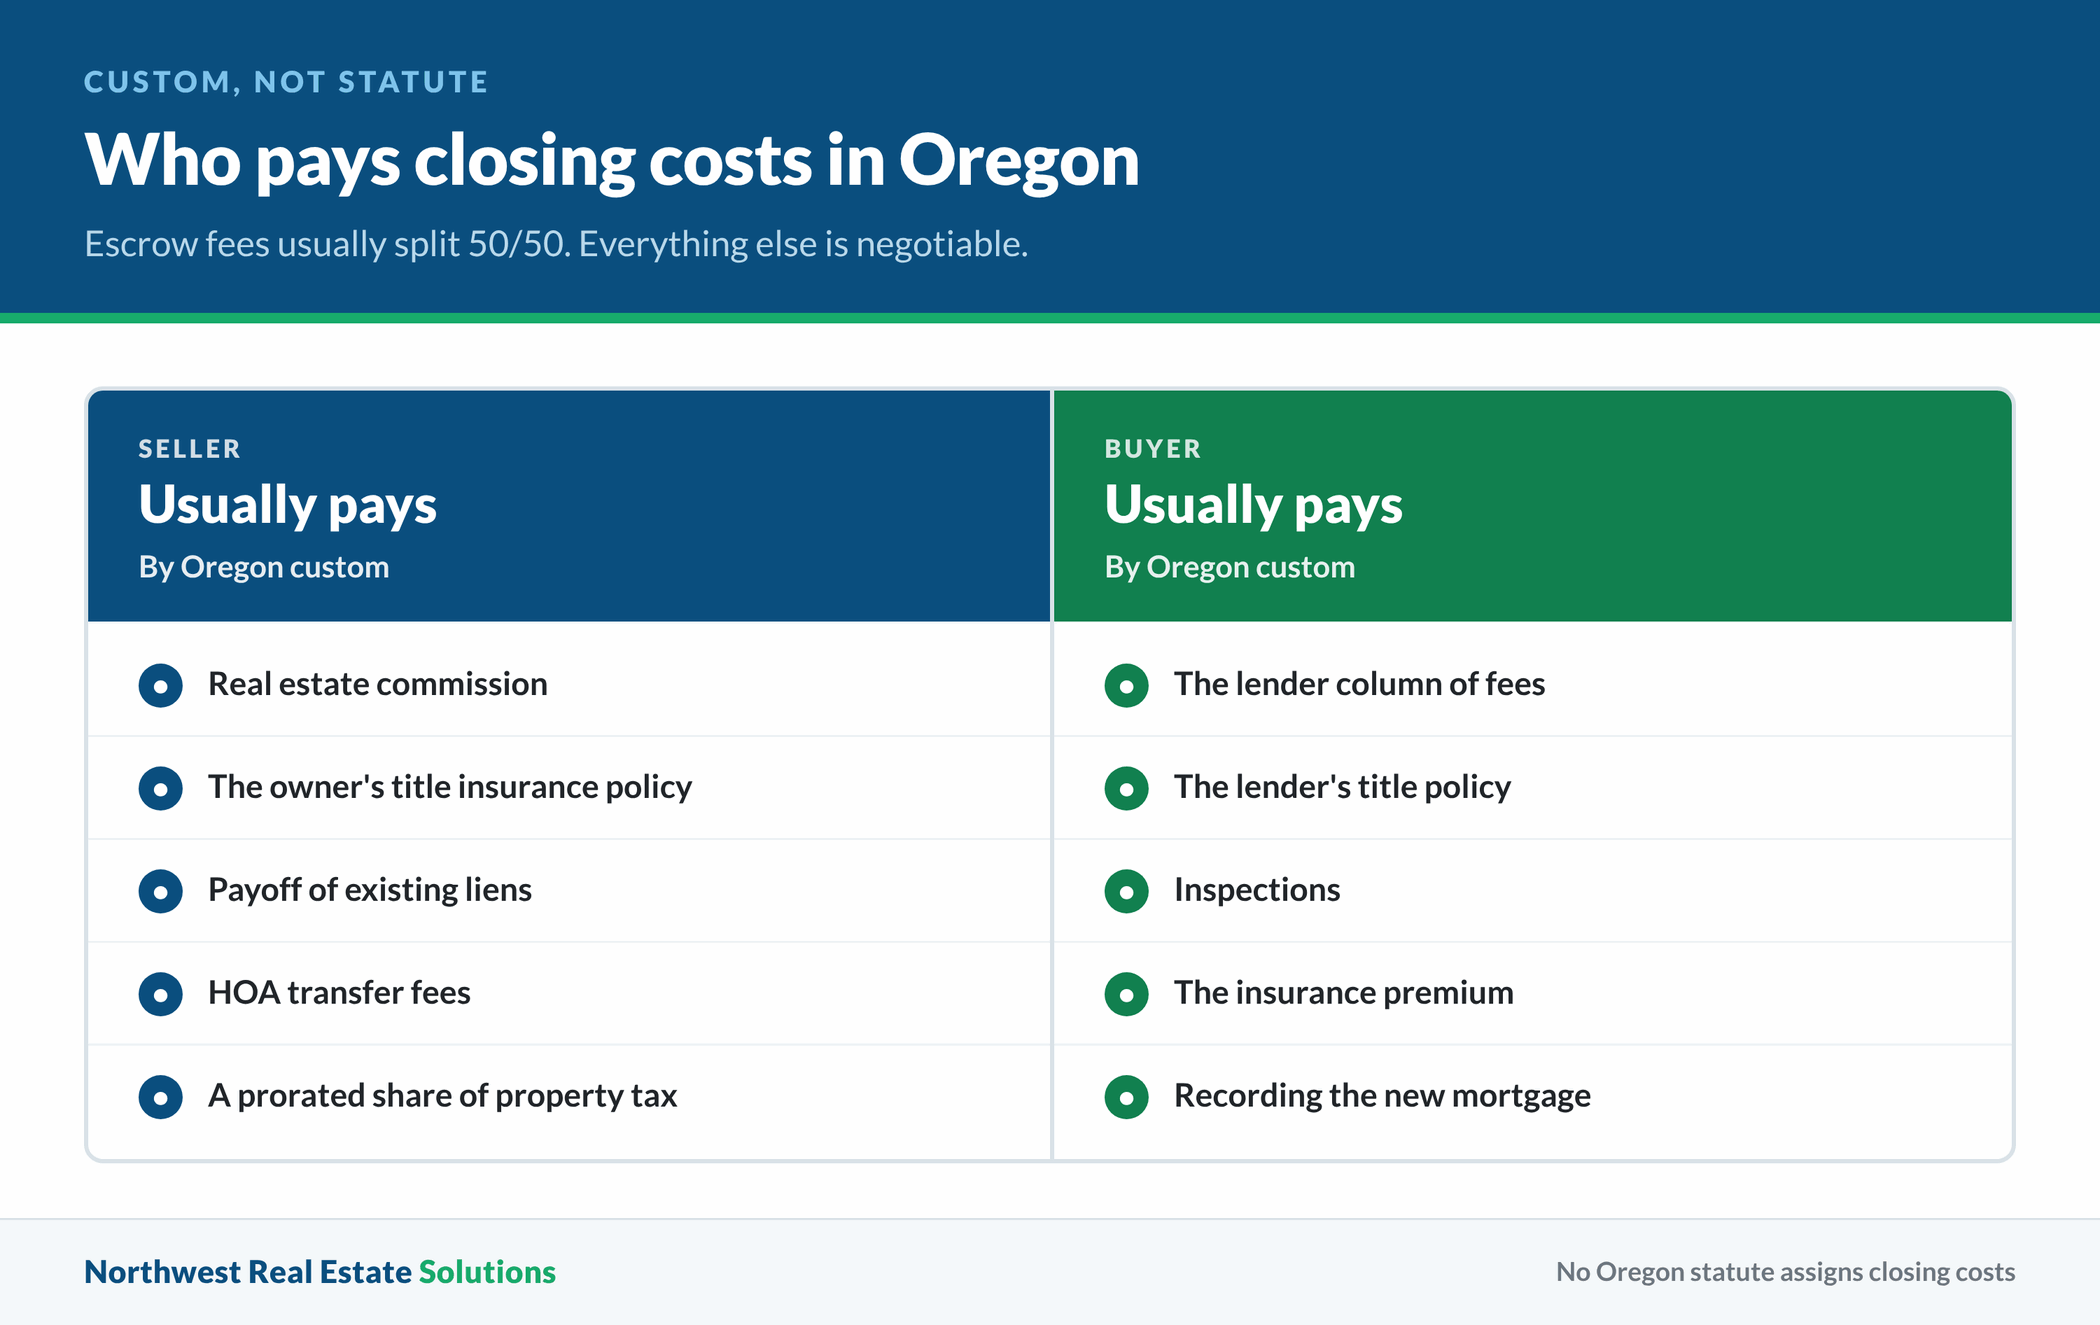
There is no Oregon statute assigning closing costs to either party. Regional custom does that job, and custom here splits escrow fees 50/50 between buyer and seller in most of the state. The owner’s title insurance policy is customarily a seller expense; the lender’s policy goes to the buyer who’s financing.
Everything else is negotiable, and in a slower market it gets negotiated hard. Buyer concessions are a normal part of Oregon sales now. A seller covering a chunk of the buyer’s loan costs is often the thing that holds a sale together after an inspection goes sideways.
Sellers almost always carry commission, the payoff of existing liens, any HOA transfer fees, and a prorated share of property tax. Buyers carry the lender column, their inspections, their insurance premium, and the recording of the new mortgage.
One caution before you start trading concessions: your lender limits how much a seller is allowed to contribute toward your costs, and that ceiling depends on your loan program and how much you’re putting down. Ask your loan officer what your limit is before you write the offer. Buyers negotiate a generous credit, feel clever about it, and then find out underwriting will only apply part of it. Anything over the line doesn’t convert to cash in your pocket either; it simply evaporates. Get the concession written into the purchase agreement as a dollar figure, not a vague promise to “help with costs,” because escrow can only disburse what the contract and the lender both recognize.
Selling as-is to a direct buyer rearranges all of this. When we buy a property through Northwest Real Estate Solutions, we cover the standard closing costs ourselves, there’s no commission on either side, and no repair credits get negotiated after the fact. That isn’t right for every homeowner. If your house is updated and your timeline is flexible, listing it will usually net you more. If it needs forty thousand in work you don’t have, the arithmetic flips.
Who pays also depends on who wants the sale more. That’s not cynicism. It’s just how negotiation works, and it’s why a seller in a hot Eugene zip code concedes less than one in a rural county with six months of standing inventory.
Why Is There a Minimum Down Payment in Oregon?
Walk into a lender’s office expecting your down payment and your closing costs to be the same conversation, and you’ll leave confused. They’re separate piles of cash, due at the same moment, for completely different reasons.
The down payment is equity. It’s your stake in the property, and lenders require a floor because borrowers with skin in the game default less often. Conventional loans generally start at a small down payment. FHA sits at 3.5 percent. VA and USDA can go to zero for those who qualify. Oregon doesn’t set these minimums; they come from the loan programs themselves and from what the secondary market will buy.
Here’s where expectations break down. Putting a small amount down on a median-priced Oregon home doesn’t shrink your closing costs one dollar. It enlarges them. A smaller down payment means a larger loan amount, resulting in a bigger origination fee, more prepaid interest, and mortgage insurance added to the monthly payment until you build equity.
I’ve watched buyers scrape together exactly the minimum down payment and then panic nine days before closing when the lender’s final figure includes several thousand in costs they’d mentally filed under “later.” Ask your loan officer for a full cash-to-close estimate at pre-approval, not at the end.
Lenders care almost as much where money comes from as how much there is. Underwriters want to see the source of every dollar: statements for the accounts the funds are sitting in and a paper trail for anything that arrived recently. If a parent is helping, that’s usually workable, but it needs a signed gift letter and a documented transfer rather than cash handed over at the kitchen table. Moving money between accounts in the weeks before closing creates work for everyone, so pick the account you’re closing from early and leave it alone. Lenders also like to see something left over after you close, so emptying every account to hit the minimum down payment can create a problem in underwriting even when the math technically works.
Oregon down payment assistance programs do exist through the state housing agency and through some county and city programs. Eligibility shifts, so check the current terms directly with the agency rather than relying on a blog post from two years ago.
How to Reduce Your Closing Costs in Oregon
A landlord in Salem called me about a duplex he’d owned since the nineties, tired of tenants and tired of repairs. He’d already paid for a listing photographer before realizing the commission alone would eat more than the new roof he’d been putting off.
Can you cut these costs meaningfully? Some of them, yes.
Shop the lender, not just the mortgage rates. Loan application and processing fees vary by hundreds between lenders on identical loan amounts, so get three loan estimates and compare page two of each, line by line. The rate gets all the attention while the fees quietly differ.
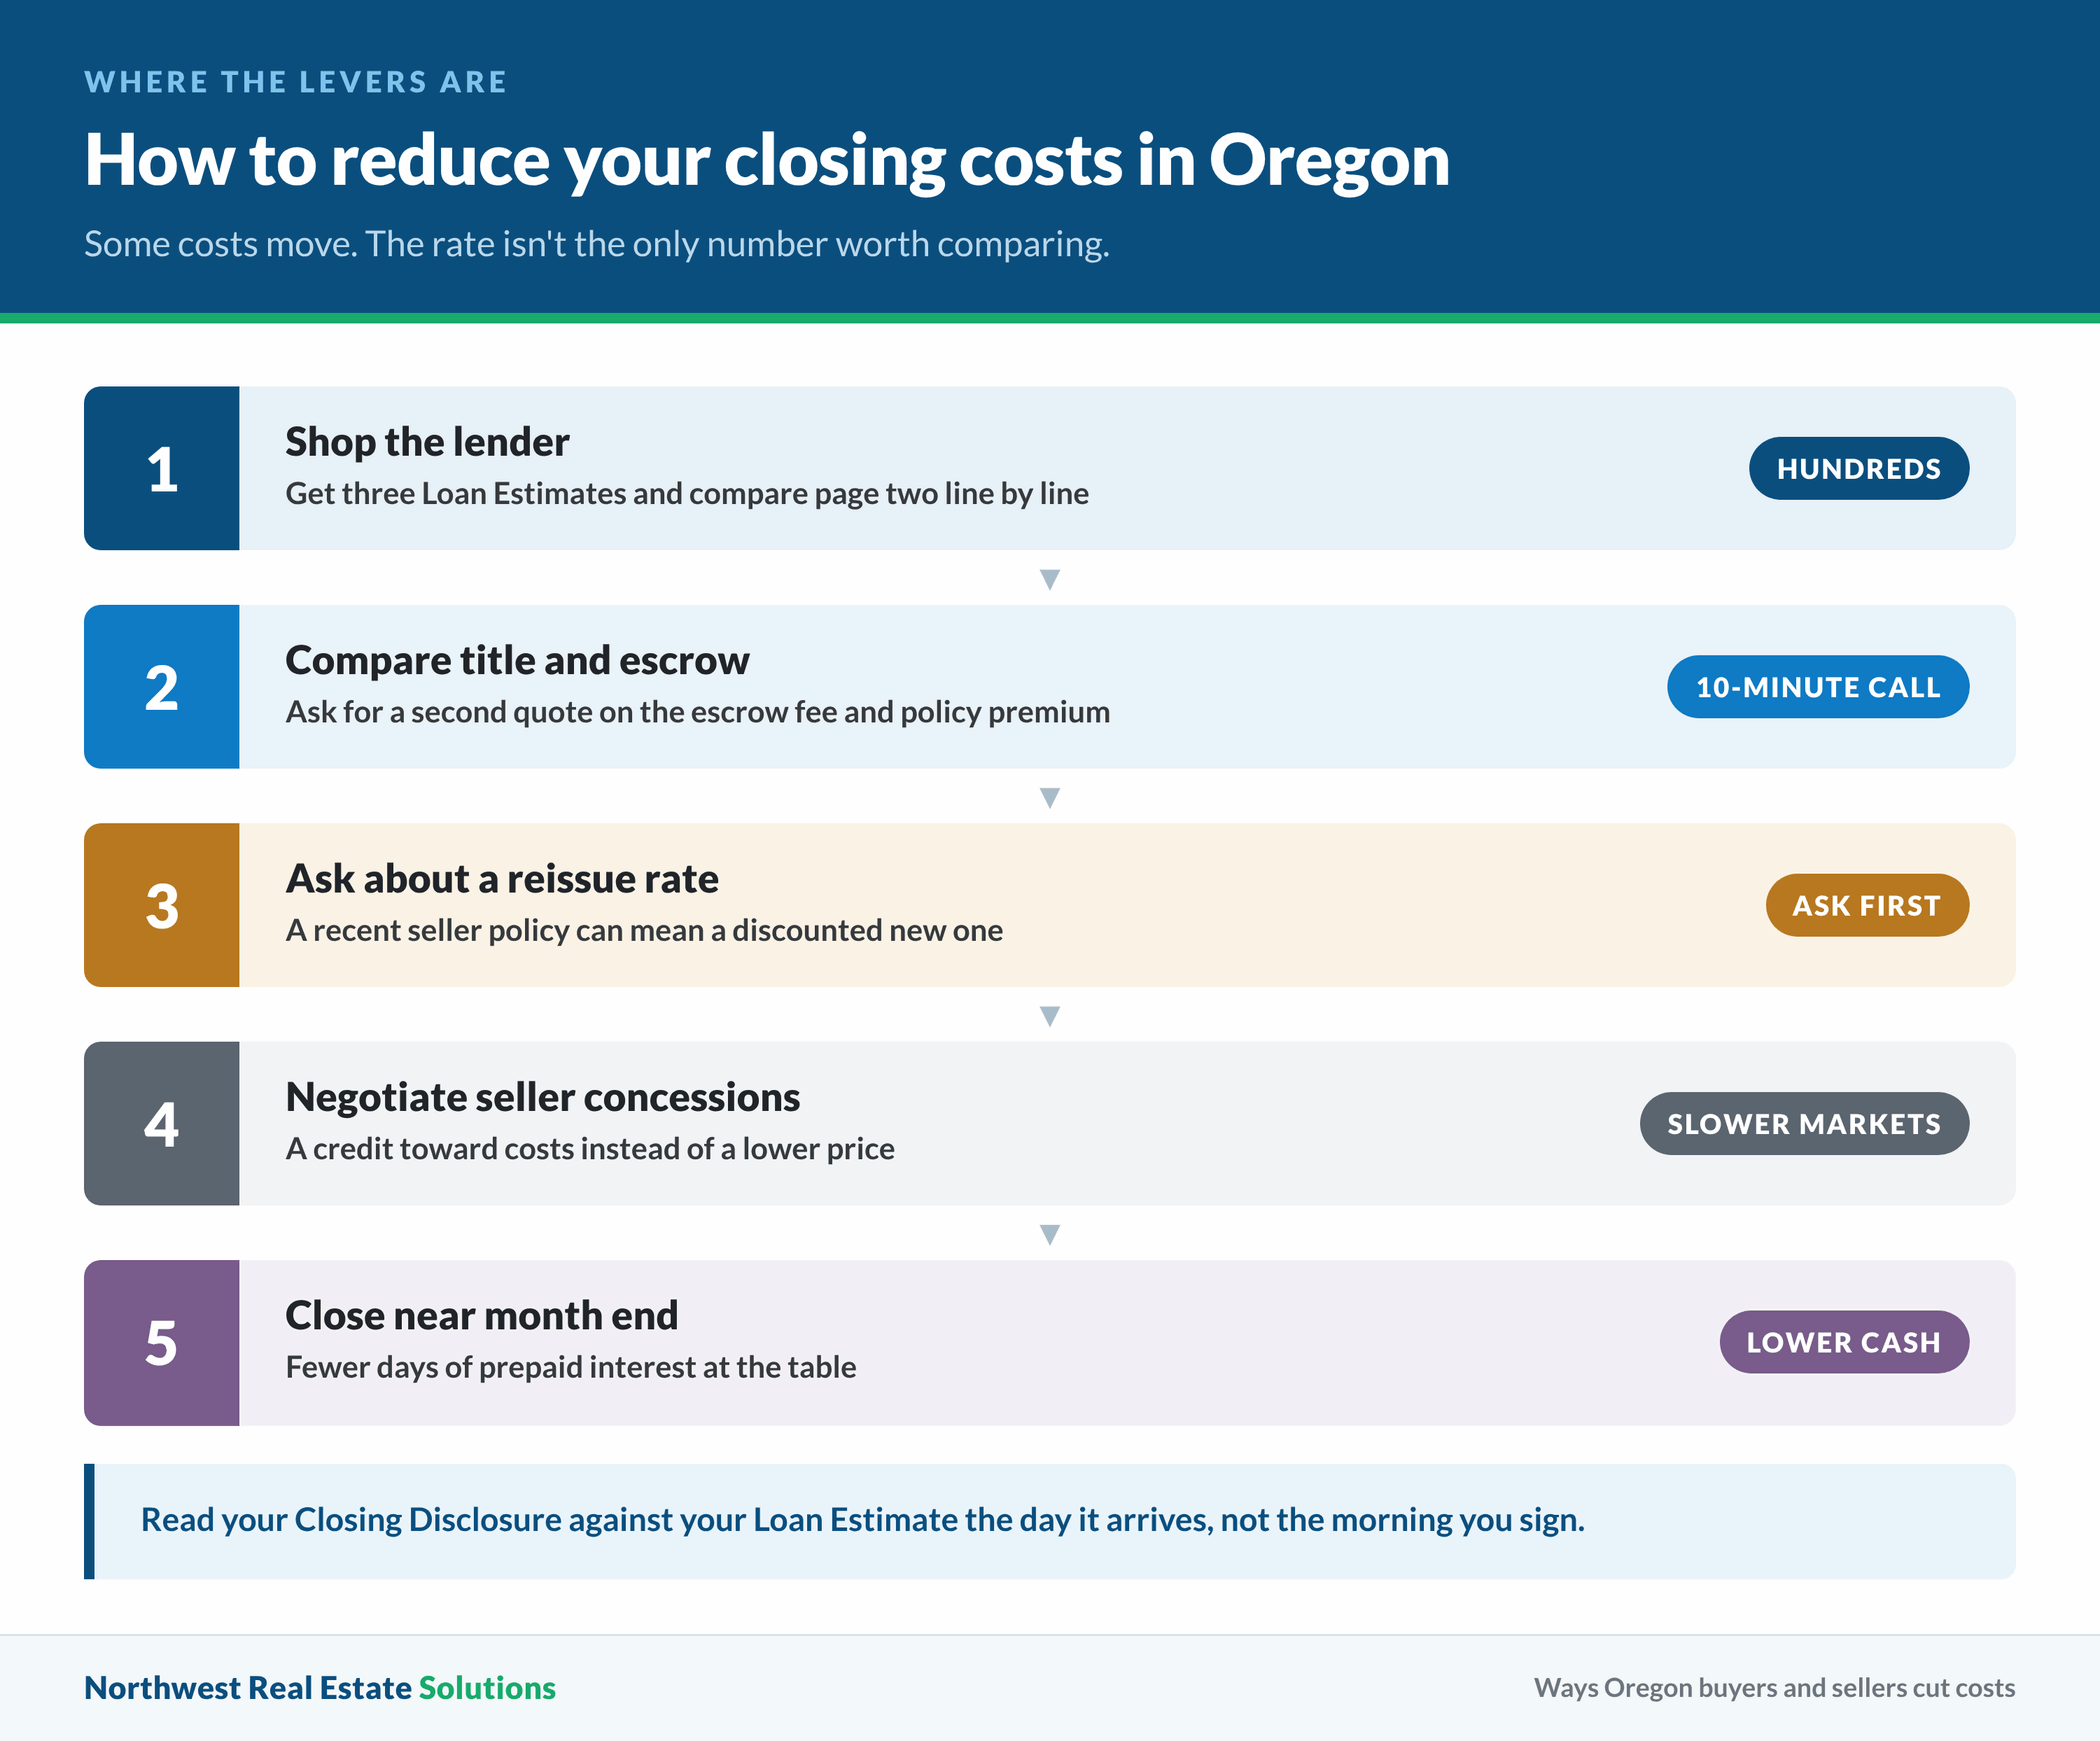
Compare title and escrow companies before choosing. Buyers assume this is assigned to them, and in most Oregon sales it’s simply whoever the agent always uses. You’re allowed to ask for a quote from someone else and compare the escrow fee and the policy premium side by side. The savings are smaller than what you’ll find on the lender column, but the phone call takes ten minutes.
Ask your title company whether a reissue rate applies. If the seller bought their policy within the last several years, a discounted rate on the new policy is sometimes available, and it won’t be offered unless you ask.
Skip discount points unless the break-even math works for your actual timeline. Paying a small fee up front to shave an eighth off your rate is a bet on staying put, and a lot of Oregon buyers move or refinance long before that break-even arrives.
Negotiate seller concessions when the market gives you room. Instead of asking for a lower price, ask the seller to credit a percentage toward your closing costs. On a slower listing, sellers tend to prefer writing a credit over dropping the sticker price, and the cash lands exactly where you need it.
If your budget’s tight, try closing near the end of the month. Prepaid interest is charged daily from closing to the end of that month, so a closing on the 28th means a few days of interest instead of three weeks of it. It doesn’t save you money over the life of the loan, but it lowers the check you write at the table.
Read your Closing Disclosure against your Loan Estimate the day it arrives instead of the morning you sign. Put them side by side and look for fees that grew, fees that appeared out of nowhere, and credits that were promised in the contract but didn’t make it onto the statement. Errors at this stage are usually clerical and usually fixable, but only if someone catches them while there’s still time to correct the figures and resend the paperwork.
Sellers have fewer levers, and the big one is commission. That’s a conversation to have before the listing agreement is signed, not after. The second lever is deciding what to fix. When an inspection report comes back long, compare what a contractor would charge you to what the buyer is asking for as a credit, because the credit is frequently the larger number and the repair is frequently the faster path. And order your loan payoff statement early. Payoff figures expire, and a stale one means a delayed closing and another day of interest you didn’t budget for.
Frequently Asked Questions
Who Pays Closing Costs in Oregon, the Buyer or the Seller?
Both, in different amounts. Buyers typically cover lender fees, appraisal, lender’s title insurance, prepaid taxes and insurance, and their half of the escrow fee. Sellers typically cover the real estate commission, the owner’s title policy, their share of property taxes, and any payoff fees on an existing loan. Nothing here is fixed by law, and everything is negotiable in the purchase agreement.
How Much Are Closing Costs in Oregon for a Buyer?
Plan on that same low-single-digit range of the purchase price, separate from your down payment. The range is wide because escrow amounts, loan type, and the timing of your tax and insurance payments all move the number.
Does Oregon Have a Real Estate Transfer Tax?
Only Washington County, which charges a transfer tax on property sales. The rest of the state is exempt under a statewide ban that grandfathered that single county.
Can Closing Costs Be Rolled Into the Mortgage?
Sometimes. Certain refinances and some loan programs allow it, and a lender credit can offset costs in exchange for a higher interest rate. On a standard purchase, most costs still need cash at the table.
When Do I Find Out My Exact Closing Costs?
Your Closing Disclosure arrives at least three business days before closing and shows final figures. Your Loan Estimate, which you get within three business days of applying, gives you a reliable preview much earlier.
We Buy Houses in Portland and Across Oregon
Portland is our home market. RMLS put the Portland metro median sale price at $540,000 in August 2026, down 1.8 percent from a year earlier. On a price like that, every percentage point of closing costs is about $5,400 out of your proceeds.
We’re cash home buyers in Portland, and we buy houses across the metro and the rest of the state. East of the city, we’re cash buyers in Gresham. South of the city, we buy houses in Lake Oswego. You can see every area on our “We Buy Houses in Oregon” page.
Compare Your Net With a Cash Offer That Covers Closing Costs
If you’re weighing a move somewhere in Oregon and the numbers still feel fuzzy, that’s normal at this stage. Bring your questions, even the ones that seem too basic to ask, and we’ll walk through what your actual cash to close would look like before you commit to anything.
When you sell to Northwest Real Estate Solutions, we cover the standard closing costs, and there’s no commission to pay. We’ll look at the house as it sits and give you a cash offer in writing. Put that number next to your estimated net from a listing, after commission, title, escrow, and repair credits, and pick the one that works for you.
Have more questions first? Check out other frequent questions. When you’re ready, fill out our quick contact us form or use the short form below.
Helpful Oregon Blog Articles
- Is the Seller Responsible for Any Repairs After Closing in Oregon?
- Can an administrator of an estate sell property in Oregon?
- Selling a Rental Property in Oregon
- Does Staging Help Sell a House in Oregon?
- How to Sell a House with Foundation Issues in Oregon
- How Much Are Closing Costs in Oregon
- Selling A House That Needs Repairs in Oregon
- Can You Sell A House Before Probate in Oregon
- Selling a House During Divorce in Oregon
- Best Time to Sell a House in Oregon
- Can You Sell a House in Foreclosure in Oregon
- Can You Sell a House With Termites in Oregon
- Sell a Distressed Home if You Live Out of State but Own in Oregon
- FSBO Costs in Oregon
- How Long Does a Real Estate Contract Last in Oregon